Buffett’s Shareholder Letters: The Best Essential Lessons (2026)

Warren Buffett Letters

For the first time in 60 years, Warren Buffett did not write Berkshire Hathaway’s annual letter to shareholders. He handed that pen to Greg Abel at the start of 2026, telling shareholders in his final Thanksgiving letter that he was “going quiet.” That single fact turns Buffett’s shareholder letters from a running series into something closed and complete.

Warren Buffett’s shareholder letters are the annual messages he wrote to Berkshire Hathaway’s shareholders from 1965 through 2024, plus one final personal note in November 2025. They report Berkshire’s results, but they’re read for something else: a plain-language education in business, risk, and investor behavior, free of the PR polish most corporate filings carry. Anyone can read the full archive on Berkshire’s own website at no cost. Greg Abel writes Berkshire’s letter now — but the 60-year Buffett archive is what most people still mean by “Buffett’s letter.”

Wall Street reads Warren Buffett’s shareholder letters for the numbers. Everyone else reads them for the fourth paragraph, where Buffett usually says the thing nobody else in finance is willing to say plainly. This guide pulls together the lessons from those shareholder letters that actually hold up — not as a highlight reel of quotes, but as ideas you can apply the next time you’re deciding what to buy, what to sell, or whether to panic.

What Are Warren Buffett’s Shareholder Letters?

Every February from 1965 to 2025, a letter signed by Warren Buffett appeared at the front of Berkshire Hathaway’s annual report. It reported the year’s results, but it did something unusual for a corporate filing: it explained the reasoning behind the results, in Buffett’s own words, without a communications team softening the language.

Buffett treated shareholders as business partners rather than an audience to be managed. He wrote about Berkshire’s failures with the same directness as its successes, named his own mistakes by name, and explained financial concepts — float, intrinsic value, owner earnings — in language a first-time investor could follow. That combination is why professional money managers and total beginners have read the same eleven pages every spring for six decades.

The letters are archived and free to read on Berkshire Hathaway’s own website, going back to 1977 in original form. Nothing about accessing them costs money, and nothing in them requires a finance degree to follow.

Why Warren Buffett’s Shareholder Letters Just Became a Complete, Closed Chapter

Context matters here, because it changes what kind of article this actually is. This isn’t a summary of one year’s letter — it’s a look back at the finished set, and the reason the set is finished just happened.

On November 10, 2025, Buffett sent what he called his Thanksgiving letter — a personal note to shareholders and his children, distinct from the formal annual report. In it, he confirmed he would step down as CEO at year-end, handing the role to Greg Abel. He said he would no longer write Berkshire’s annual report or speak at length at the shareholder meeting. He’d keep sending the Thanksgiving letter, he wrote, but the tradition he started in 1965 — one CEO, one voice, one letter a year explaining the business — was over.

Abel became CEO on January 1, 2026. His first annual letter to shareholders, covering Berkshire’s 2025 results, was dated February 28, 2026. He opened it by calling Buffett “arguably the greatest investor of all time,” and used much of the letter to write down Berkshire’s culture and capital-allocation principles explicitly for the first time — something Buffett had mostly conveyed through decades of accumulated example rather than a single stated list.

None of this makes Buffett’s own letters less useful. If anything, it’s the opposite. A 60-year body of work you can read start to finish, from a 34-year-old buying a failing textile mill to a 95-year-old handing the keys to his chosen successor, is a more complete education than any single year’s letter could be. A good starting discipline, before you read a single lesson below: pull up how to actually evaluate a company’s numbers yourself, so the lessons have something concrete to attach to.

Berkshire’s 60-Year Scorecard: What the Numbers Actually Show

Buffett included one table in nearly every letter he wrote: Berkshire’s per-share market value against the S&P 500, year by year, going back to 1965. It’s one of the most audited scorecards in investing, because Buffett published the misses right alongside the wins, every single year, without exception.
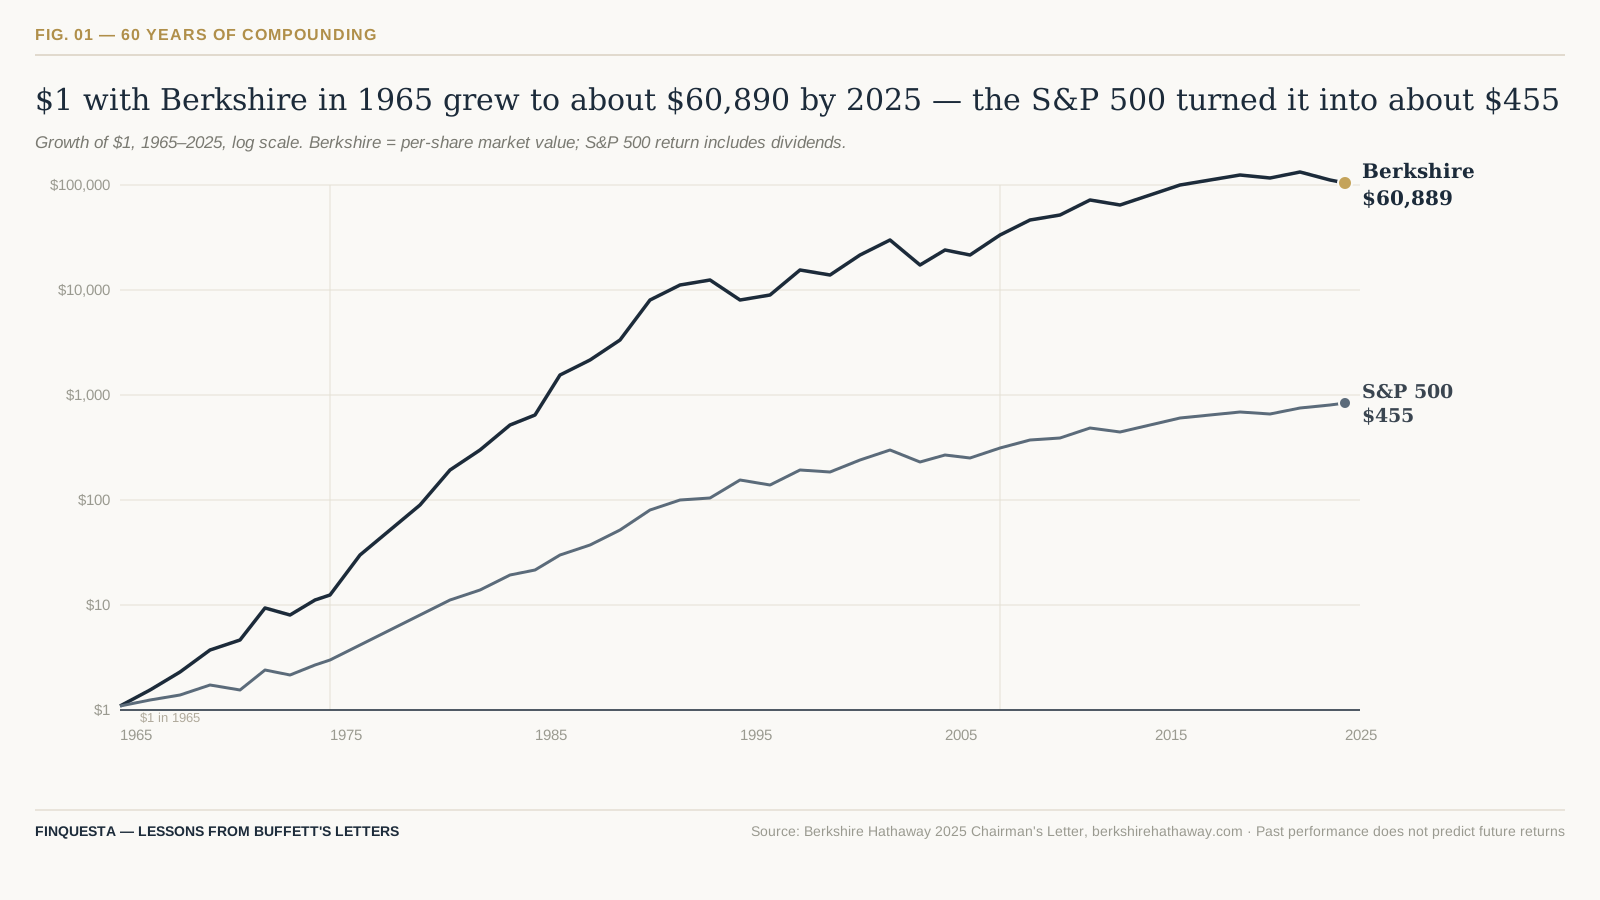
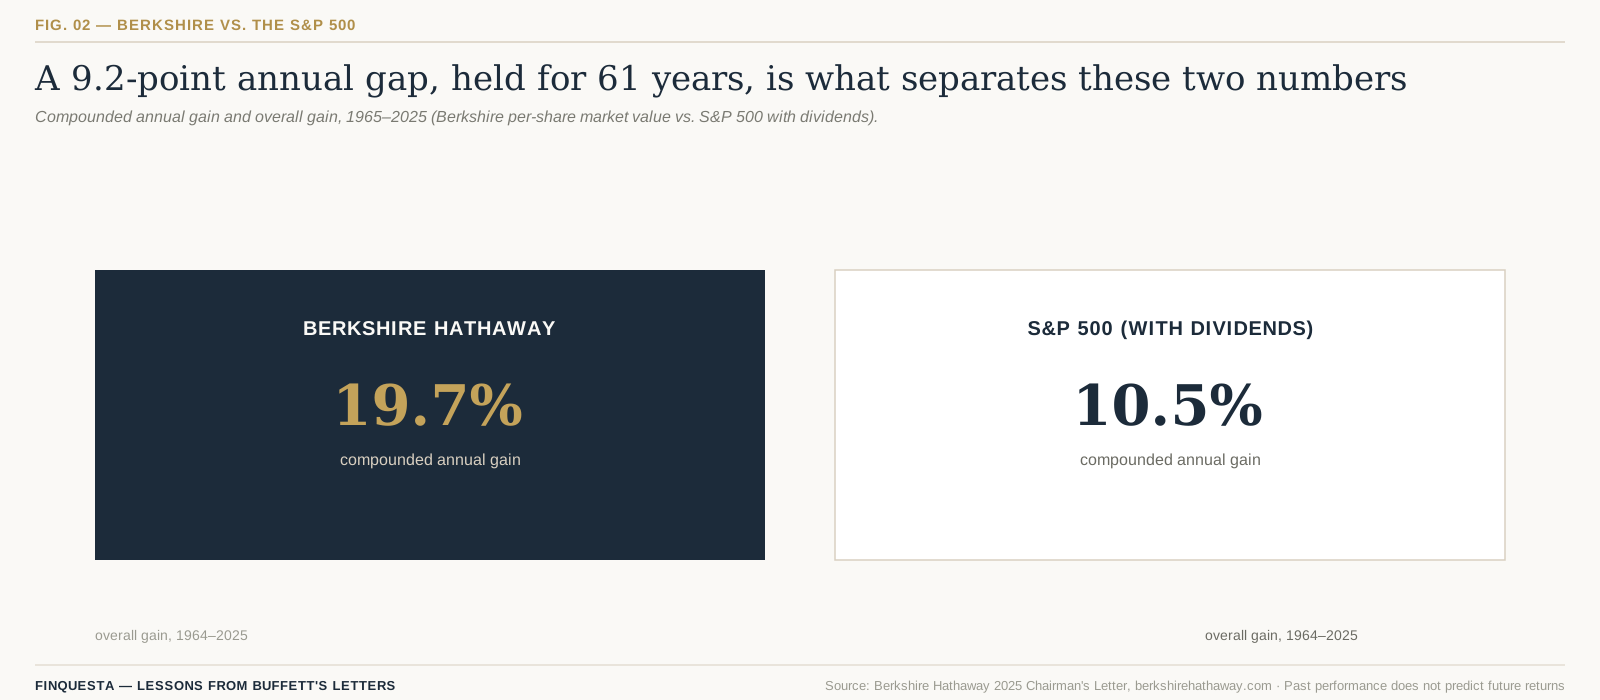
Over 1965–2025, Berkshire’s per-share market value compounded at 19.7% a year. The S&P 500, dividends included, compounded at 10.5% a year. That 9.2-point annual gap, held for six decades, is the entire reason a $1 stake in 1965 grew to roughly $60,890 in Berkshire versus roughly $455 in an S&P 500 tracker.
Two things in that table matter more than the headline number. First, Berkshire didn’t win every year — it lost badly in 1974 (-48.7%), 1990 (-23.1%), 1999 (-19.9%), and 2008 (-31.8%), each time in a year the S&P 500 also fell or came close to it. An investor watching only the down years would have seen four separate reasons to quit.

Second, the gap between the two lines didn’t come from avoiding those bad years at all. It came from what happened in the years in between them, which is the actual subject of nearly every lesson in this guide. Skimming past the losing years to get to the compounding is exactly the habit this article is trying to talk you out of.

None of this happened in a vacuum, either. The same discipline that built the scorecard is still visible in how Berkshire deploys capital today: in 2025 alone, Abel’s team added two very different businesses to Berkshire — OxyChem, an industrial chemicals producer, and Bell Laboratories, a family-owned pest-control company whose owner wrote directly to Buffett describing a durable, easy-to-understand business with a strong management team. Neither purchase makes headlines the way a flashy tech acquisition would. That’s rather the point of the whole approach.

Circle of Competence: Buffett’s First Rule for Not Losing Money

In his 1996 letter, Buffett laid out the idea most people now know by a three-word label — circle of competence — though that exact phrase is a later shorthand rather than his own original wording. His own words were plainer: an investor doesn’t need to understand every company, only the ones inside the boundary of what they actually understand. Knowing where that boundary sits, he wrote, matters more than how large the circle is.

Greg Abel’s 2026 letter borrowed a sports analogy Buffett had used for decades to describe the same discipline. Buffett drew inspiration from Ted Williams, the baseball Hall of Famer who divided the strike zone into 77 cells and swung only at pitches in his highest-percentage zone. Williams hit .344 for his career by refusing to swing at anything else. Buffett applied the same logic to companies: wait for the ones you understand well enough to judge, and let the rest go by unswung.

This is where the circle of competence gets misread most often. It isn’t a rule about avoiding complexity — Berkshire owns railroads, reinsurance contracts, and utility infrastructure, none of which are simple businesses. It’s a rule about honesty with yourself, not a rule about difficulty. Buffett passed on internet stocks through the entire dot-com run not because he thought the businesses were too advanced to learn, but because he judged that he couldn’t reliably tell which ones would still exist in ten years.

For an Indian investor scanning a stock screener, the practical version of this lesson is a question, not a rule: could you explain, in three sentences and without jargon, how this specific company will actually make money five years from now? If the honest answer is no, the circle of competence says wait — not never, just not yet, and not on this particular stock until that changes.

The Patience Lesson: Investing to Hold Forever

In his 1989 letter, describing why Berkshire had just bought large stakes in Coca-Cola and Freddie Mac preferred stock, Buffett wrote a line that outlived the specific investments it described: when Berkshire owns part of an outstanding business with outstanding management, “our favorite holding period is forever.”

The line gets quoted often enough that it’s easy to miss what it’s actually claiming. Buffett isn’t saying never sell — Berkshire has sold plenty of positions over the decades, including some he once called permanent. He’s making a narrower claim: the businesses worth owning are worth owning through the discomfort of a bad quarter, a bad year, or in Berkshire’s case, entire bad stretches measured against the index.

Go back to that 60-year scorecard above. Berkshire fell more than 20% in three separate years — 1974, 1990, and 2008 — and each time it went on to post some of its strongest years within the following five. An investor who sold Berkshire stock in early 1975, convinced the -48.7% year proved something was broken, missed a 129.3% recovery the very next year.

The pattern isn’t unique to Berkshire. It’s the mechanical reason patience shows up in almost every durable investing framework, from Buffett’s letters to a plain-vanilla Nifty 50 SIP: most of the compounding happens in a small number of very good years. You only collect them if you’re still holding on the day they arrive, which is a much harder thing to guarantee than it sounds.

Be Greedy When Others Are Fearful — And Vice Versa

Buffett’s contrarian instinct is easy to state and hard to actually practice, which is exactly why it shows up in almost every “Buffett lessons” list you’ll find — usually without an example of what it actually costs to act on it in real time.

Here’s one. In September 2008, with Lehman Brothers days from collapse and the entire financial system visibly seizing up, Berkshire invested $5 billion in Goldman Sachs preferred stock carrying a 10% dividend. Every visible signal in the market that week said retreat. Buffett bought into the panic instead, on terms he’d negotiated because Goldman needed capital and few other buyers were willing to commit it at that specific moment.

The lesson underneath the famous line isn’t simply buy when markets fall. Markets fall often, and plenty of falling markets keep falling for good reason. The lesson is narrower and harder than that: Buffett was only willing to be greedy because he’d already done the circle-of-competence work on Goldman’s underlying business, and the fear in the market that week was about liquidity and sentiment, not about whether the business itself was sound. Contrarian timing without that homework done first isn’t courage — it’s a bet wearing a better story.

Don’t Be a Preening Duck — Judge Yourself Against a Benchmark

In his 1998 letter, reporting on a strong year, Buffett reached for a specific image to warn against a specific mistake: a duck that paddles through a rainstorm and rises with the flood water, then mistakes the rising water for its own paddling skill. He asked shareholders to judge Berkshire’s “duck rating” not by whether it went up, but by how much it went up relative to every other duck on the same pond.

That year, the pond was the S&P 500, and it had risen almost as fast as Berkshire had. This is a harder habit than it sounds, because it cuts both ways. A portfolio up 15% in a year the market is up 25% feels like a win and is actually a loss of relative ground; a portfolio down 10% in a year the market is down 20% feels like a loss and is actually real outperformance.

Most retail investors never build the habit of checking against a genuine benchmark, because checking sometimes tells you your good year wasn’t earned. It was just water.

Bet on the Economy That Employs You

In one of his final traditional letters, Buffett described what he called the American Tailwind: the idea that betting against the country whose growth had done most of the work in Berkshire’s own returns had never once made sense across his 80 years of investing, however loudly any given year’s headlines argued otherwise.

The specific claim in that letter is American. The structure underneath the claim isn’t. Buffett’s point wasn’t patriotism for its own sake — it was that a diversified bet on a large, dynamic, growing economy has historically rewarded patience more reliably than trying to out-guess which sector or which year will outperform next.

For an Indian investor, the same structural logic points toward India’s own growth rather than America’s. A broad-based Nifty 50 or Nifty 500 index fund is a direct, low-cost way to hold that particular bet, without needing to correctly guess which individual company captures the growth first.

It’s worth being precise about what this lesson does and doesn’t say. It isn’t advice to ignore valuation, or to buy any index at any price, at any time. It’s an argument against the specific, recurring mistake of sitting in cash for years because a headline made the near future look uncertain — which, if you check any five-year stretch of financial news, it always does.

The Casino Now Resides in Many Homes: Speculation vs. Investing

In one of his last letters, Buffett drew a line between investing and what markets increasingly reward instead: activity for its own sake. He observed that today’s market participants aren’t more emotionally disciplined than earlier generations were. If anything, the tools for constant trading have moved from a trading floor into everyone’s pocket, and what he called the casino now sits inside people’s own homes rather than a building they’d have to travel to.

The distinction he was drawing matters more now than when he wrote it. An app that makes buying a stock as frictionless as ordering food doesn’t just lower costs — it removes the natural pause that used to sit between an emotional impulse and an executed trade. Buffett’s point wasn’t that trading apps are bad in themselves. It’s that frequent activity isn’t the same thing as good investing, and mistaking one for the other is an expensive way to learn the difference between them.

The Float Multiplier: Why You Can’t Just Copy Buffett’s Returns

Original Finquesta framework.

Here’s the coverage gap in almost every “lessons from Buffett” article: they’ll tell you to hold Coca-Cola forever, and they’ll rarely explain why buying the same stock Buffett bought doesn’t hand you the same result Buffett got. The missing piece isn’t stock selection at all. It’s structural, and it’s called float.
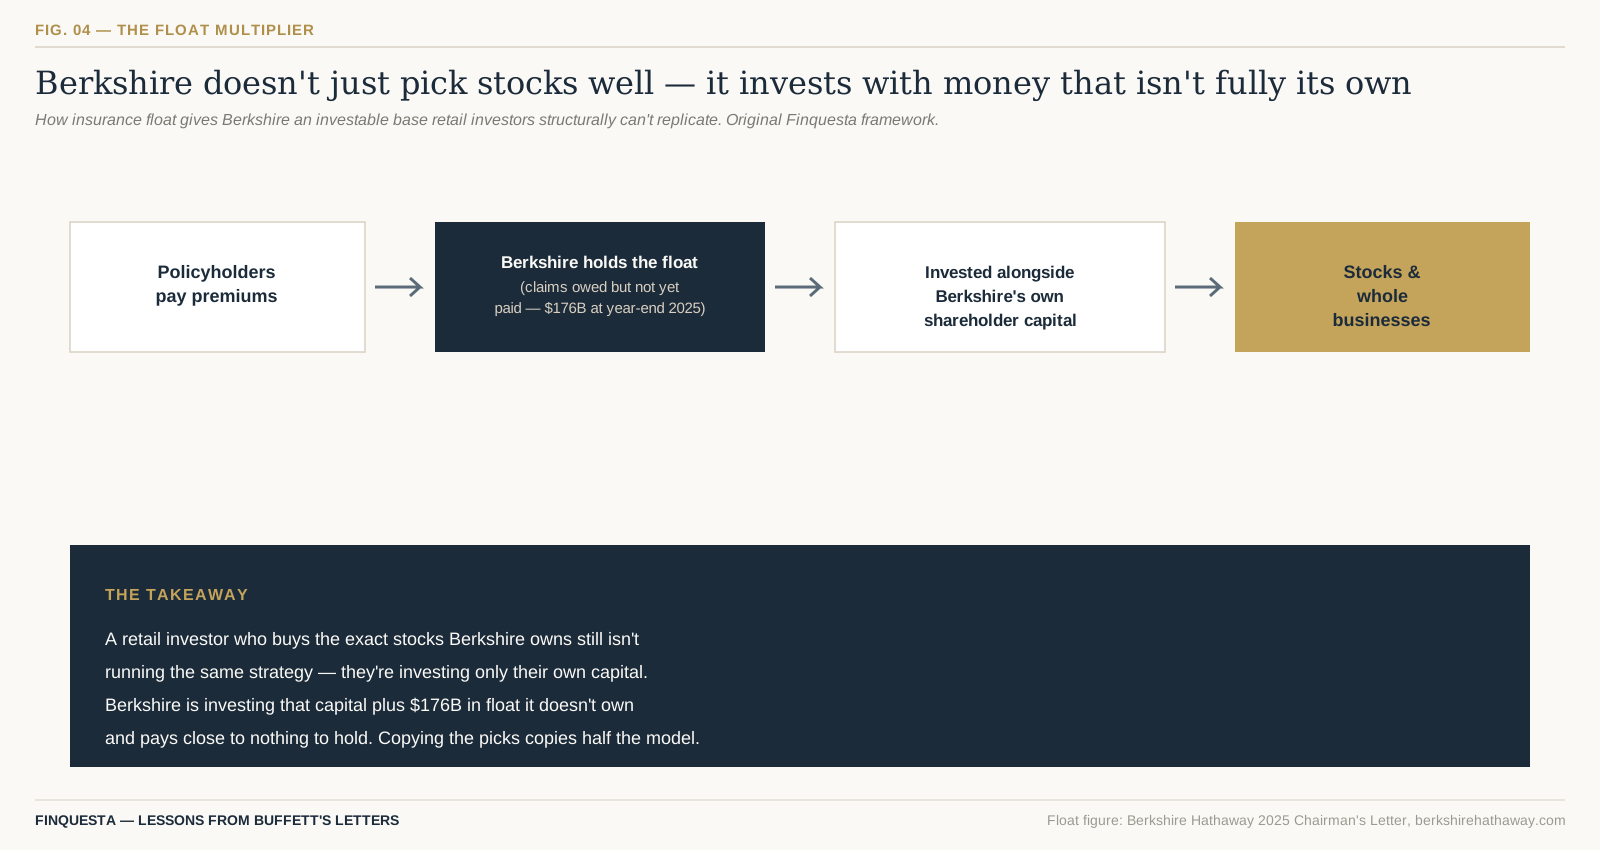
Berkshire’s insurance businesses collect premiums up front and pay claims later, sometimes decades later. In the meantime, that money — the float — sits on Berkshire’s balance sheet. It isn’t Berkshire’s money in an ownership sense; it’s money Berkshire temporarily holds and gets to invest until it’s owed back out. At the end of 2025, that float stood at $176 billion, up from $88 billion just a decade earlier.

Call this the Float Multiplier: Berkshire has spent six decades investing not just its shareholders’ own capital, but a second, enormous pool of money that costs close to nothing to hold and doesn’t have to be repaid on any individual investor’s schedule.

A retail investor who buys Apple, American Express, Coca-Cola, and Moody’s — Berkshire’s four largest holdings, worth a combined $158.6 billion at the end of 2025 — is investing their own capital in the same four companies. They are not investing with a second pool of float sitting alongside it. Copying the stock list copies, at most, half of the actual mechanism.

This isn’t a reason to give up on equity investing — it’s a reason to stop expecting Berkshire’s 19.7% to be a personal benchmark. Even Abel’s own 2026 letter is candid about this ceiling from the inside: at Berkshire’s current size, he wrote, the math of compounding now works against further outsized gains, and the honest goal going forward is steady per-share growth rather than another six decades at the historical rate.

If sheer size works against the $1 trillion company that actually has the float, the comparison was never fair for an individual SIP in the first place. That should be reassuring, not discouraging, once you see why the two numbers were never meant to line up.

The Mistake Ledger: What Buffett’s Biggest Errors Teach You

Original Finquesta framework.

Every “Buffett lessons” article mentions that he admits mistakes. Almost none of them build that habit into something you can actually use yourself. Here’s a working version: four of Buffett’s own admitted errors, in order, each with what it cost and where he said so.
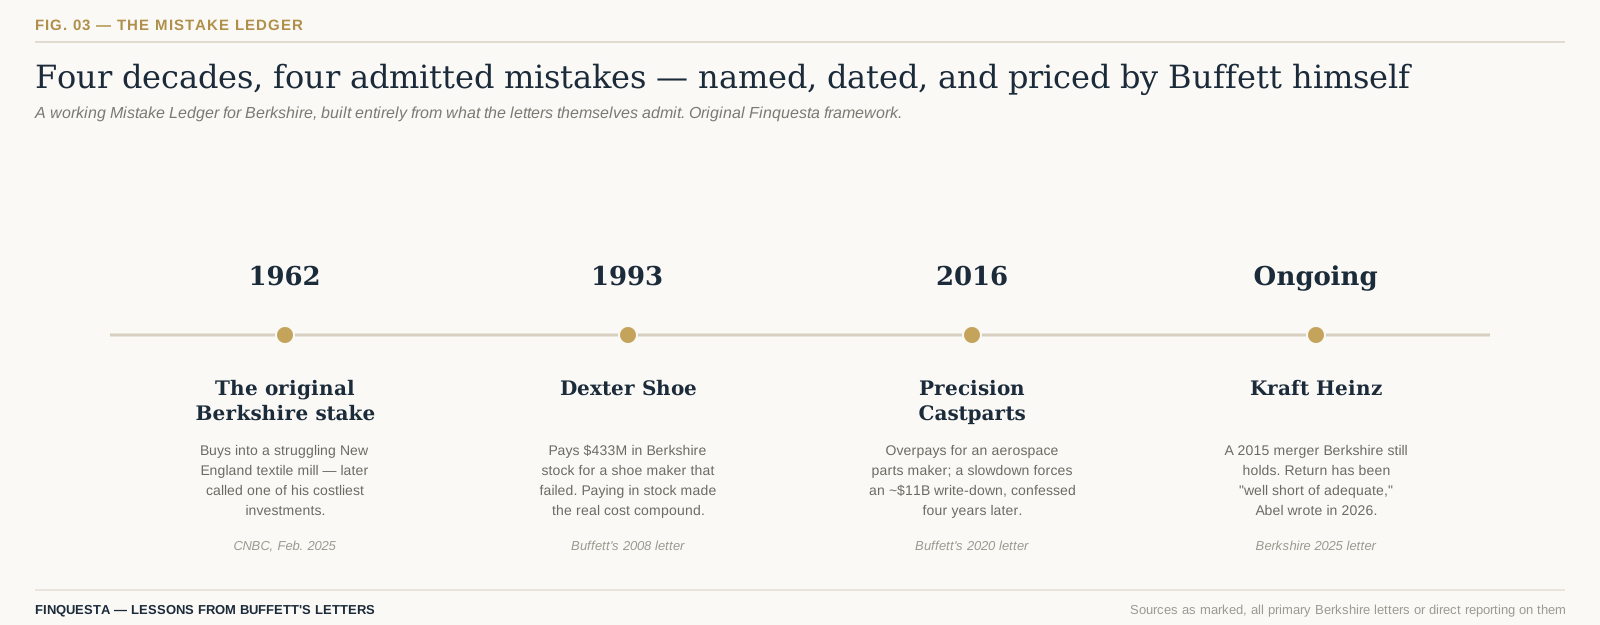
The pattern across all four isn’t the specific mistake — it’s the format of the admission. Buffett didn’t bury these in footnotes or vague language. He named the company, named the number, and named the year, in the same letter format he used to report Berkshire’s wins. That’s the actual transferable habit: not a private promise to never make mistakes, which nobody can honestly keep, but a standing commitment to write down what went wrong, what it cost, and why, on a fixed annual schedule, whether or not anyone asks.

A personal Mistake Ledger doesn’t need Berkshire’s scale to be useful. Once a year — tax season is a natural trigger for Indian investors already gathering financial documents — write down every investment decision you’d genuinely reconsider, what you were thinking at the time, and what actually happened afterward. The value isn’t in the guilt of reviewing it.

It’s in the pattern that emerges after three or four annual entries, which is usually more specific and more useful than “be more careful.” Often it’s something like a recurring tendency to sell winners too early, or to buy only after a stock has already moved — invisible in any single year, obvious across five.

A minimal entry might read: sold a holding in March after a 20% drop, reasoning at the time was fear the decline would continue, and six months later it had fully recovered while the money moved into something that returned less. One sentence, one honest number, no self-punishment attached — just a record you can actually search next year.

What Actually Changes Now That Greg Abel Is CEO

Berkshire shareholders have spent a year absorbing this question, and the honest answer is: less than the headlines suggested, in the parts that matter most to how the company is actually run — and more than zero, in a few specific, named places.

What doesn’t change: Buffett remains Berkshire’s Chairman, in the office five days a week, and Abel’s 2026 letter is explicit that Berkshire continues to draw on his judgment in that role. Berkshire’s decentralized structure — autonomous operating businesses, minimal head-office bureaucracy, managers who think like owners — is the piece Abel’s letter spent the most space defending, quoting Charlie Munger’s own line from 2021 that “Greg will keep the culture.”

What does change: Abel now holds sole capital-allocation authority, a role Buffett held for six decades by himself. Berkshire’s approach to some capital-heavy bets may shift, too — one prominent Berkshire-watcher, quoted in CNBC’s coverage of Abel’s first letter, suggested Abel may prove more willing than Buffett was to deploy Berkshire’s large cash position at today’s rates rather than holding it in short-term Treasuries.

Structurally, the annual letter itself has changed shape. It’s no longer a single founder’s voice reflecting on a year gone by — it’s now a CEO’s letter in a more conventional sense, even with Abel deliberately writing it in Buffett’s spirit and even quoting Buffett directly within it.

Two smaller transitions are unfolding inside the same letter. Marc Hamburg, Berkshire’s CFO for decades, is retiring effective June 2027 and begins handing his responsibilities to successor Chuck Chang in mid-2026. Berkshire also named Mike O’Sullivan as its first-ever General Counsel. Buffett has called Hamburg indispensable to both the company and to himself personally — a reminder that Berkshire’s institutional continuity was never really a one-man operation, even in the decades when the letter carried only one signature.

None of this is a reason to treat Berkshire, or the lessons in its 60-year archive, any differently than before. The letters were never really about one man’s individual stock picks. They were a public record of a specific way of thinking about risk, patience, and honest disclosure — and that record doesn’t get rewritten just because a different person is now holding the pen.

Reading Warren Buffett’s Shareholder Letters as an Indian Investor

Almost everything in Warren Buffett’s shareholder letters was written for an American reader holding American securities, which means the useful move for an Indian investor is translation, not imitation. Three specific gaps are worth naming directly, rather than glossing over.

First, tax treatment. Berkshire pays no dividend and rarely sells, which is itself a tax strategy under the U.S. system — deferring capital gains indefinitely by simply not realizing them. India’s capital gains rules for equity are structured differently, and change often enough with each year’s Union Budget that stating a specific current rate here would go stale fast. Check the current short-term and long-term capital gains treatment for equity directly on the Income Tax Department’s site before making any decision that hinges on holding period.

Second, the specific stocks themselves. Buffett’s four largest U.S. holdings aren’t available to most Indian retail investors without additional cost and complexity: international investment limits, currency conversion, and extra compliance all apply. The lesson worth taking isn’t “buy Apple.” It’s the evaluation process that led there, reapplied to companies actually available on the NSE and BSE.

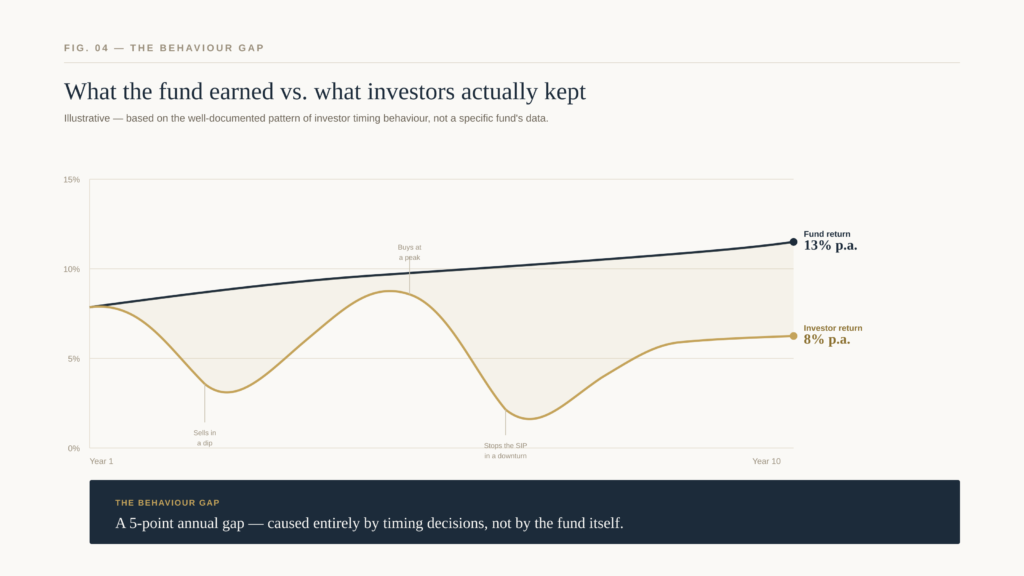
Third, and most directly useful: Finquesta has already written about the gap between what investors know and what they actually do under pressure, specifically for Indian SIP investors — the tendency to pause or stop a SIP right at the moment a market fall makes it most valuable to keep going.

That behavior gap is the same failure Buffett’s letters warn about, visible in the 1974, 1990, and 2008 rows of his own performance table above. Reading a table of Berkshire’s worst years is a low-stakes way to practice recognizing that feeling before it costs you something in your own portfolio.

Where These Lessons Don’t Translate Directly

A fair account of Buffett’s letters has to include what doesn’t carry over cleanly. This is the section most “Buffett lessons” articles skip entirely, usually because admitting limits is less satisfying to write than admitting genius.

Berkshire buys entire private businesses, not just shares of public ones. A meaningful share of Buffett’s actual edge — the kind described in Abel’s letter as capital deployed with “no financing contingency attached” — comes from being able to acquire whole companies on terms no individual investor can access at all. Circle of competence and patience are genuinely transferable skills. That specific channel of returns simply isn’t, for anyone reading this.

Berkshire’s size is now itself a constraint, not an advantage, by the company’s own admission. Abel’s letter says this plainly: at Berkshire’s scale, the math of compounding works against further outsized growth going forward. A retail investor with a modest portfolio doesn’t share that particular constraint, which cuts both ways — smaller means more flexible, but it also means none of the float, negotiating leverage, or first-call access to deals that make up the rest of Berkshire’s structural edge described in the Float Multiplier above.

And finally, a boundary worth stating outright: this article, like every Finquesta guide, describes how to evaluate an approach. It isn’t a recommendation to buy Berkshire Hathaway shares, any Indian equity, or any specific security, and nothing in it should be read as one.

How to Actually Read an Annual Letter — Yours, Not Just Berkshire’s

The most practical habit in Warren Buffett’s shareholder letters has nothing to do with stock-picking. It’s the discipline of the letter itself: a plain-language, once-a-year account of what happened, what you got right, what you got wrong, and why it happened. Nothing stops an individual investor from writing their own version of one.

Set a fixed date. Buffett’s letters arrived every February without fail, year after year. Pick a date tied to something you already do annually — filing taxes, a birthday, the start of a new financial year — so the review isn’t optional or dependent on your mood that week.

Report the number honestly, first. Write down your actual portfolio return for the year, and the return of a relevant benchmark like the Nifty 50 or Nifty 500 for the same period, before you write anything else. This is the preening-duck check from earlier in this guide, applied to your own year instead of Berkshire’s.

Name one mistake and one thing that worked. Not vaguely — specifically, with the decision, your reasoning at the time, and what actually happened afterward. This is a Mistake Ledger entry in miniature, and it’s the single habit most likely to change your decisions the following year.

Write it down, not just think it. The difference between a genuine annual review and a vague New Year’s resolution is that Buffett’s version existed on paper, was dated, and could be checked against next year’s letter. A note in your phone that you’ll actually reread in twelve months does the same job just as well.

Reread last year’s before you write this year’s. Buffett’s letters gained their power cumulatively — each one assumed the reader remembered the last one’s admissions and promises. Five minutes with your own prior entry, before writing a new one, is what turns a snapshot into an actual track record.

Common Myths About Buffett’s Investing Style

MythWhat the letters actually show
Buffett trades constantly to stay ahead of the marketBerkshire’s hallmark is extremely low turnover — some positions have been held for decades, and Buffett has repeatedly said his favorite holding period is forever
Buying Berkshire stock today recreates Buffett’s historical returnsPast compounding at 19.7% a year reflects six decades of float, deal access, and a smaller starting size — Abel’s own letter says Berkshire’s current scale now works against repeating that rate
Buffett has never made a serious investing mistakeBuffett named and priced his own errors publicly nearly every year, including Dexter Shoe, Precision Castparts, and the original Berkshire textile business itself
Circle of competence means only investing in simple businessesIt means only investing where you can judge the underlying economics — Berkshire owns railroads and reinsurance contracts, neither of which is simple
Buffett is against ordinary people buying index fundsHe has repeatedly recommended low-cost index funds for investors who don’t want to actively evaluate individual businesses themselves

Frequently Asked Questions

What is Warren Buffett’s most famous shareholder letter lesson?

The most quoted line is probably his 1989 remark that when Berkshire owns part of an outstanding business with outstanding management, its favorite holding period is forever. It’s less a rule against ever selling and more an argument for judging businesses by their multi-decade economics rather than their next quarter.

Is Warren Buffett still writing Berkshire Hathaway’s annual letter?

No. Buffett wrote every annual letter from 1965 through the letter covering 2024 results, published in February 2025. He announced in a November 2025 Thanksgiving letter that he was stepping down as CEO and would no longer write the annual report. Greg Abel, Berkshire’s new CEO, wrote the first Abel-authored annual letter in February 2026.

What is Berkshire Hathaway’s average annual return?

Per Berkshire’s own reported table, Berkshire’s per-share market value compounded at 19.7% annually from 1965 through 2025, versus 10.5% for the S&P 500 with dividends included. That historical rate isn’t a forecast: Berkshire’s own 2026 letter notes that the company’s current size now works against repeating it going forward.

Can I read Warren Buffett’s shareholder letters for free?

Yes. Berkshire Hathaway publishes the full archive of annual letters, going back to 1977 in original form, free on its official website, with no signup or payment required.

What is Warren Buffett’s “circle of competence”?

It’s the idea, from his 1996 letter, that an investor doesn’t need to understand every company — only the ones inside the boundary of what they can genuinely evaluate. Buffett has said the size of that circle matters less than knowing exactly where its edges sit.

Should Indian investors copy Warren Buffett’s stock picks?

Not directly. Buffett’s largest holdings are U.S. stocks with different tax treatment, currency exposure, and access requirements for Indian residents. The transferable part is his evaluation process — circle of competence, patience, and judging performance against a benchmark — reapplied to companies actually available on the NSE and BSE.

What was Warren Buffett’s biggest investing mistake?

Buffett named several candidates himself across different letters, including the original 1962 purchase of Berkshire Hathaway as a textile company, and the 1993 Dexter Shoe acquisition, which he called his worst deal in his 2008 letter because he paid $433 million in Berkshire stock that would otherwise have kept compounding for decades.

Who is Greg Abel, and why does he matter to Berkshire shareholders?

Greg Abel became Berkshire Hathaway’s CEO on January 1, 2026, succeeding Warren Buffett, who remains Chairman. Abel previously ran Berkshire’s non-insurance operations and was publicly named as Buffett’s chosen successor years before the transition took effect. His February 2026 letter was the first Berkshire annual letter not written by Buffett since 1965.

What is Berkshire Hathaway’s “float,” and why does it matter?

Float is the pool of premium money Berkshire’s insurance businesses hold temporarily before paying out claims. It stood at $176 billion at the end of 2025. Berkshire invests this money alongside its own shareholder capital, a structural source of its returns that an individual investor copying Berkshire’s stock holdings does not have access to.

How is Buffett’s approach different from just buying an index fund?

Buffett actively evaluates individual businesses within his circle of competence, while an index fund buys the entire market without that judgment. Notably, Buffett himself has repeatedly told most ordinary investors to skip individual stock-picking altogether and buy low-cost index funds instead — advice that sits somewhat apart from how Berkshire itself actually invests its own capital.

Does Berkshire Hathaway pay a dividend?

No. Berkshire has never paid a cash dividend under Buffett’s tenure, and Abel’s 2026 letter confirms the policy continues: the company won’t pay one as long as each retained dollar is reasonably likely to create more than a dollar of market value for shareholders. The Board reviews this policy every year.

What happened to Warren Buffett’s Thanksgiving letter tradition?

It continues. Even after stepping down as CEO and handing off the formal annual shareholder letter, Buffett said in November 2025 that he would keep sending a personal Thanksgiving letter to shareholders and his children each year — a smaller, separate tradition from the annual report he no longer writes.

Disclaimer

This article is for informational and educational purposes only and does not constitute financial, investment, tax, or legal advice. Figures, rates, and regulations mentioned are subject to change; please verify current details with official sources (RBI, SEBI, the Income Tax Department, IRS, or a licensed financial advisor) before making financial decisions. Finquesta may earn a commission from affiliate links in this article at no extra cost to you.
Compound Interest: How It Builds Wealth in 2026

Compound Interest

Compound interest is what happens when the interest your money earns starts earning interest of its own, instead of being paid out separately. Anyone with a savings account, fixed deposit, PPF account, mutual fund, or retirement account is already using it, knowingly or not — and anyone carrying a credit card or loan balance is subject to the exact same mechanism in reverse. There’s no minimum amount needed for it to work; it applies to ₹500 exactly as it applies to ₹50 lakh. What changes the outcome isn’t the starting amount — it’s the rate, the frequency, and above all, the time you leave it alone.

What Compound Interest Really Means

Most people meet compound interest for the first time through a credit card statement, not a retirement calculator.

You carry forward a balance one month. The next bill is a little higher than what you spent — not just because of new purchases, but because of what you already owed. Leave it a few months longer and the growth isn’t steady anymore; it’s accelerating. A ₹50,000 balance at a fairly typical Indian credit card rate of 36% a year, compounding monthly with no payments at all, would grow past ₹1,00,000 in well under two years. That’s the same mechanism, working in the direction most of us meet it first.

Compound interest, explained without the mythology: your money earns a return, that return gets added to your balance, and the next round of earnings is calculated on the new, larger total. That’s it. Everything else in this guide — the formula, why growth feels slow at first, where compounding actually shows up in your accounts, and where it quietly works against you — is just that one idea, followed through to its real consequences.

In the direction that builds wealth instead of debt, compound interest is simply this: the interest your money earns doesn’t sit off to the side. It gets folded back into the balance, and the next round of interest is calculated on the new, larger number. Then that happens again. And again. Every cycle, the base gets a little bigger, so every subsequent round of interest is calculated on more than the round before it.

You’ll often see this called “the eighth wonder of the world,” usually attributed to Einstein. It’s worth being precise about that, because Finquesta would rather lose a good line than repeat a bad citation: there’s no verified record Einstein ever said it.

Quote Investigator, the reference project that traces misattributed quotations back to their source, found the earliest print appearance in unsigned 1920s bank advertising copy, with the specific Einstein attribution not showing up until 1983 — 28 years after his death, with no citation attached. Princeton’s own edited volume of his quotes files it under “Probably Not By Einstein.”

None of that makes the underlying math less real. It just means you don’t need a borrowed authority to make the point — the numbers do that on their own.

Simple Interest vs. Compound Interest: The Difference That Compounds

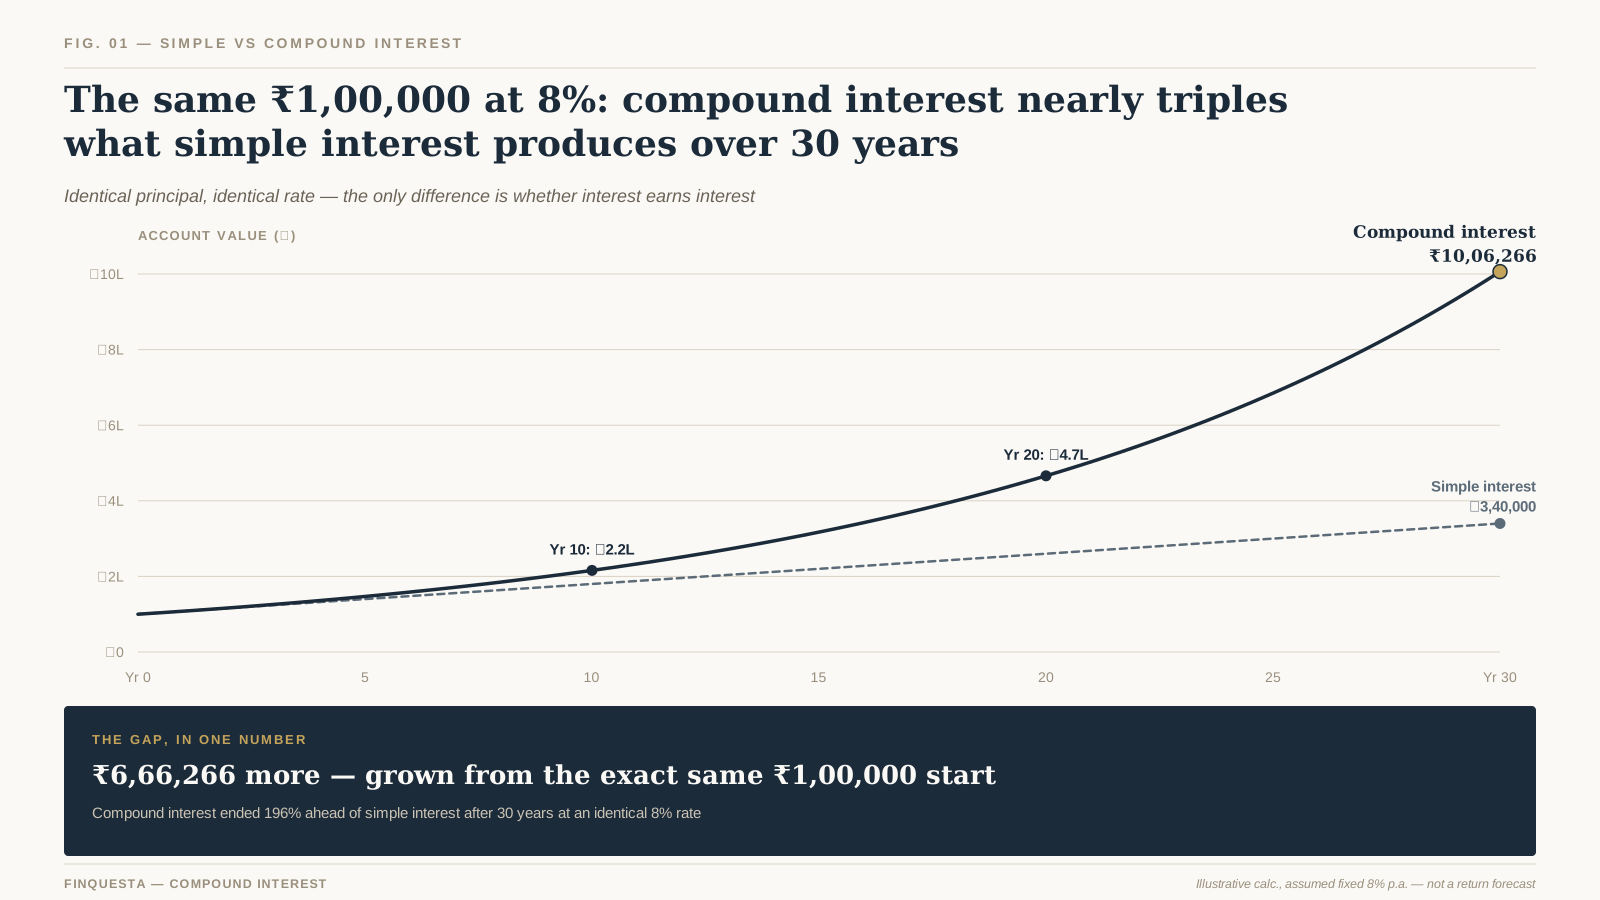
Here’s the comparison that actually explains why compounding matters, using a single lump sum so the two methods are directly comparable: ₹1,00,000, at an assumed 8% a year, for 30 years.

Under simple interest, you earn 8% of the original ₹1,00,000 every single year — always ₹8,000, no matter how long the money has been sitting there. After 30 years, that’s ₹1,00,000 principal plus 30 × ₹8,000, or ₹3,40,000 total.

Under compound interest, each year’s 8% is calculated on the current balance, not the original one. Year one looks almost identical to simple interest — ₹1,08,000 either way. By year ten, compound interest has pulled ahead to roughly ₹2.16 lakh against simple interest’s ₹1.8 lakh. By year thirty, compound interest has grown to just over ₹10 lakh — nearly three times what simple interest produced from the exact same starting amount and the exact same rate.

compound interest

FIG. 01 — Simple vs compound growth of the same ₹1,00,000 over 30 years at an assumed 8% p.a.

Nothing changed except how the interest was treated. That gap — roughly ₹6.66 lakh on a ₹1 lakh starting point — is the entire argument for compound interest in one comparison.

The Compound Interest Formula, Broken Down

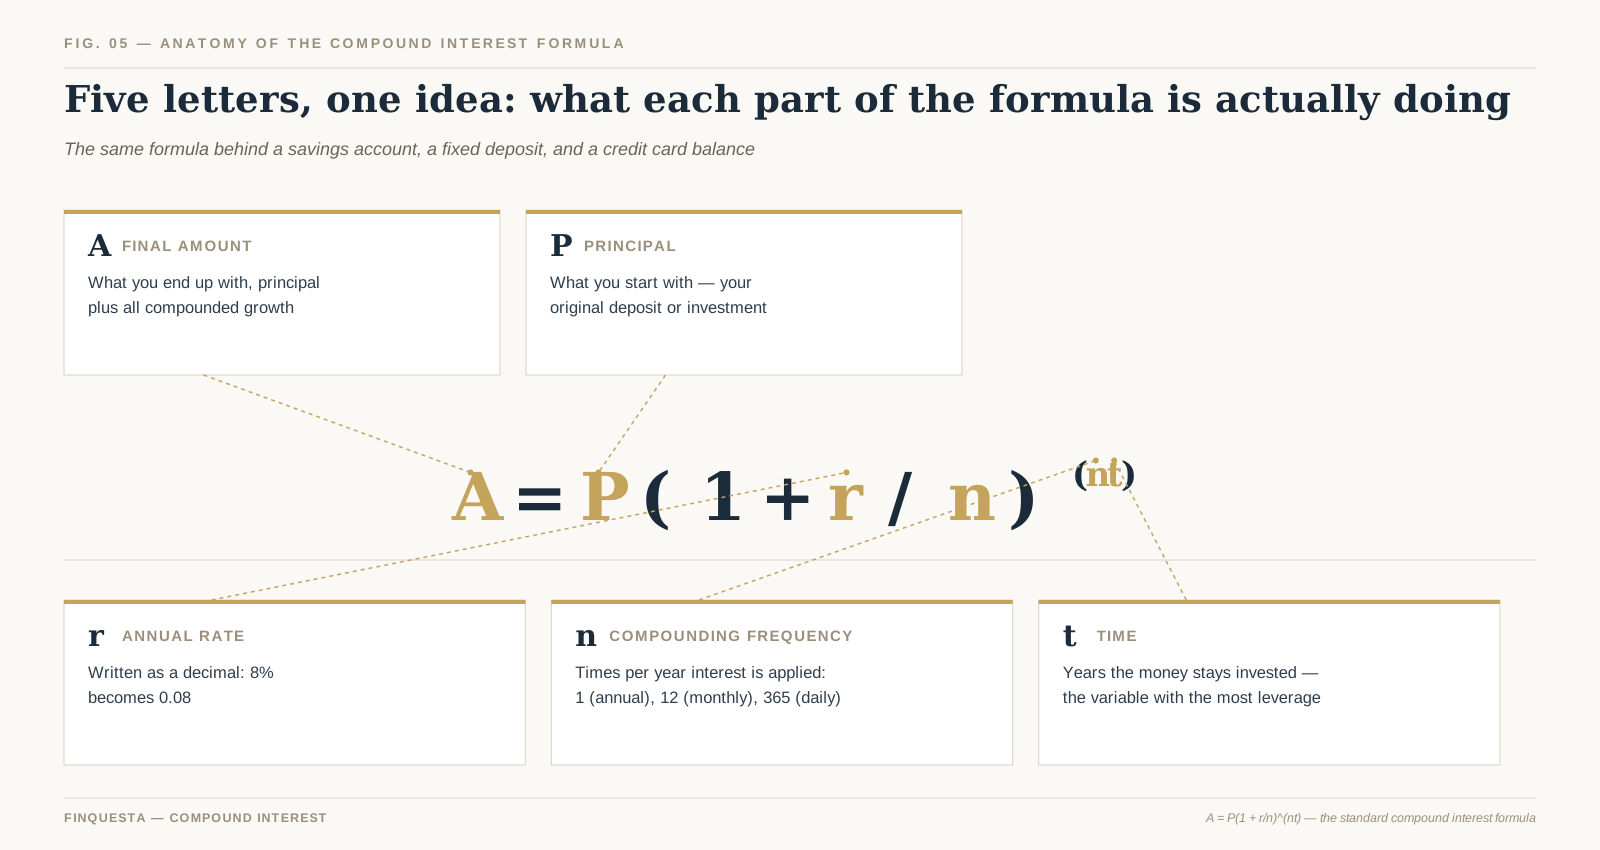
The standard formula looks intimidating until you see what each piece is actually doing:

A = P (1 + r/n)^(nt)

  • A is the amount you end up with
  • P is your principal — what you start with
  • r is the annual interest rate, written as a decimal (8% becomes 0.08)
  • n is how many times per year the interest compounds (1 for annual, 12 for monthly, 365 for daily)
  • t is the number of years you leave it invested
compound interest

FIG. 05 — Anatomy of the compound interest formula: A = P(1 + r/n)^(nt)

If you’re contributing regularly instead of depositing one lump sum — a monthly SIP, a recurring deposit, a salary-linked retirement contribution — the formula changes shape slightly (it becomes a future-value-of-annuity calculation), but the underlying logic doesn’t change at all: each contribution starts compounding from the day it lands, so your earliest contributions do disproportionately more work than your most recent ones, simply because they’ve had longer to compound. That single fact is the reason the next two sections exist.

Why Compounding Feels Slow at First: The Quiet Decade

ORIGINAL FINQUESTA FRAMEWORK

Take a fairly ordinary example: investing ₹10,000 every month at an assumed 12% average annual return — a commonly used long-term assumption for diversified equity investing in India, though real returns will vary year to year and are never guaranteed. Run that for 30 years and look at what the growth (not the contributions — the growth alone) looks like, broken into three ten-year blocks:

FIG. 02 — The Quiet Decade: growth by decade on a ₹10,000/month SIP at an assumed 12% p.a. (Original Finquesta framework)

  • Years 1–10: you’ve put in ₹12 lakh. The account has grown to about ₹23 lakh. Growth from interest alone: roughly ₹11 lakh — about 3.5% of the growth this plan will eventually produce.
  • Years 11–20: same monthly amount, same rate. Growth from interest alone in this decade: roughly ₹63.9 lakh — about 20.4% of total lifetime growth.
  • Years 21–30: growth from interest alone in this final decade: roughly ₹2.39 crore — about 76.1% of everything this plan will ever earn.

Three equal ten-year stretches. Identical monthly contribution. Identical assumed rate. And the last one does more than three times the work of the first two combined.

We call the first stretch the Quiet Decade — not because nothing is happening (the math is working exactly as designed, every single month), but because almost nothing is visible yet. A chart of this account over its first ten years looks close to a straight line. It’s only once you’re well into the second decade that the curve starts to visibly bend upward, and only in the third decade that it becomes the dramatic, headline-friendly hockey stick every finance article likes to show you.

This is, as far as we can tell, the actual reason most people quit long-term investing early rather than because the maths stopped working: the first several years genuinely do look unimpressive next to the amount you’re putting in, and there’s no visual cue telling you the shape is about to change. If you know the Quiet Decade is coming, you can recognise it for what it is — the unglamorous, unavoidable setup phase — instead of mistaking it for the plan not working.

This is also the direct, quantified answer to a question that comes up constantly: does starting five years late really cost that much? Using the exact numbers above: someone who starts this plan on time reaches roughly ₹3.49 crore at year 30. Someone who starts five years late — same monthly amount, same rate, just beginning at what would have been year six — is only 25 years into their own timeline by that same calendar point, with a corpus of roughly ₹1.88 crore. A five-year delay, on total contributions that differ by only ₹6 lakh, produces a final-corpus gap of roughly ₹1.62 crore — because those five lost years weren’t just five years of missed contributions, they were five years removed from the most productive end of the curve, not the flattest end.

The Crossover Point: When Growth Starts Outpacing Your Own Contributions

ORIGINAL FINQUESTA FRAMEWORK

Here’s a more useful milestone than “the earlier the better,” because it’s specific enough to actually calculate for your own numbers.

Using the same ₹10,000-a-month, 12%-assumed example: for the first several years, whatever you contribute in a given year is larger than whatever the account earns in that same year. You are still doing more work than your money is. Then, at a specific point, that flips — the growth earned in a single year becomes larger than the amount you contributed that year, and from then on, the gap keeps widening in your favour every year that follows.

FIG. 03 — The Crossover Point: annual growth overtakes the annual contribution in year 7 (Original Finquesta framework)

In this example, that point arrives in year 7: the account earns roughly ₹1,39,600 in growth during year 7 alone, against ₹1,20,000 contributed that year. From year 7 onward, your money is contributing more than you are, every single year, by a growing margin.

We call this the Crossover Point, and unlike “start early,” it isn’t just encouragement — it’s a specific, calculable year that changes based on your own contribution amount and assumed rate. A higher assumed return or a smaller monthly contribution pulls the Crossover Point closer; a lower rate or a larger monthly amount pushes it further out. Either way, it turns an abstract concept into a real date on a real calendar you can actually look forward to, which tends to matter more for staying consistent through the Quiet Decade than any encouragement to “just be patient” ever does.

Does Compounding Frequency Actually Matter?

Every compound interest article mentions that more frequent compounding — monthly instead of annual, daily instead of monthly — produces a larger final number. That’s true. What’s less often shown is how much larger, because the honest answer undercuts the drama.

Take ₹1,00,000 at an assumed 8% annual rate for 20 years:

Compounding frequencyFinal amountDifferen Zce vs. annual
Annual₹4,66,096
Monthly₹4,92,680+₹26,584 (5.7%)
Daily₹4,95,216+₹29,121 (6.2%)

Monthly versus daily — the two frequencies most often compared in marketing material — differ by about ₹2,536 over 20 years on a ₹1 lakh base, or roughly 0.5%. Frequency matters, and it’s a real, mathematically legitimate reason to prefer an account that compounds more often, all else equal. But it is a rounding error next to the two variables that actually move the outcome: the rate you’re earning, and the time you stay invested. If a bank’s pitch leans heavily on “daily compounding” as the headline reason to choose it over a comparable option with a better rate, the frequency isn’t the thing worth chasing.

The Rule of 72: A Shortcut, Not a Substitute

The Rule of 72 estimates how many years it takes an amount to double: divide 72 by the annual interest rate. At 8%, that’s 72 ÷ 8 = 9 years. It’s a genuinely useful mental-math shortcut — but it’s an approximation, and it’s worth knowing exactly where it holds up and where it starts to drift, rather than treating it as exact in every context.

RateRule of 72 estimateActual doubling time
6%12.00 years11.90 years
7.1% (PPF, current rate)10.14 years10.11 years
8%9.00 years9.01 years
12%6.00 years6.12 years
18%4.00 years4.19 years
36% (typical Indian credit card rate)2.00 years2.25 years

The rule is nearly exact in the 6–10% range — which happens to be roughly where long-term fixed-income and blended equity-debt returns tend to sit, which is probably why the rule became popular in the first place. Above about 15%, it starts understating the real doubling time, and the gap widens as the rate climbs. At credit-card-level rates, the Rule of 72 tells you your debt doubles in 2 years when the real figure is closer to 2.25 — a meaningful understatement exactly where getting it wrong costs you the most.

When Compound Interest Works Against You: Debt

Every mechanism described so far runs identically in reverse. A credit card issuer isn’t doing anything mathematically different from a bank paying you interest — they’re applying the same formula, with you on the other side of it.

At a representative Indian credit card rate of 36% a year, compounded monthly, an untouched ₹50,000 balance — assuming genuinely no payments are made at all, which is a worst-case illustration, not a typical outcome — grows past ₹1,00,000 in about 23 months, under two years. Real cards require a minimum payment each month, which slows this considerably, but paying only the minimum still leaves the bulk of the balance compounding against you month after month — which is precisely why minimum-payment-only debt is so difficult to work down even when the monthly payment feels manageable.

This is the same mechanism from the earlier sections, in a mirror. The Quiet Decade and the Crossover Point both describe compounding working slowly in your favour, then accelerating. Debt compounds on exactly the same schedule — slowly at first, then faster — except every month it isn’t paid down is a month working against you instead of for you. Understanding the mechanism is what makes the difference obvious: the goal isn’t to fear compound interest, it’s to make sure you’re consistently on the side of it that’s working for you.

The Tax Leak: How Taxation Quietly Slows Down Compounding

ORIGINAL FINQUESTA FRAMEWORK

Almost no beginner explanation of compound interest accounts for tax — but tax changes the compounding math directly, because money paid out in tax each year is money that stops compounding from that point forward.

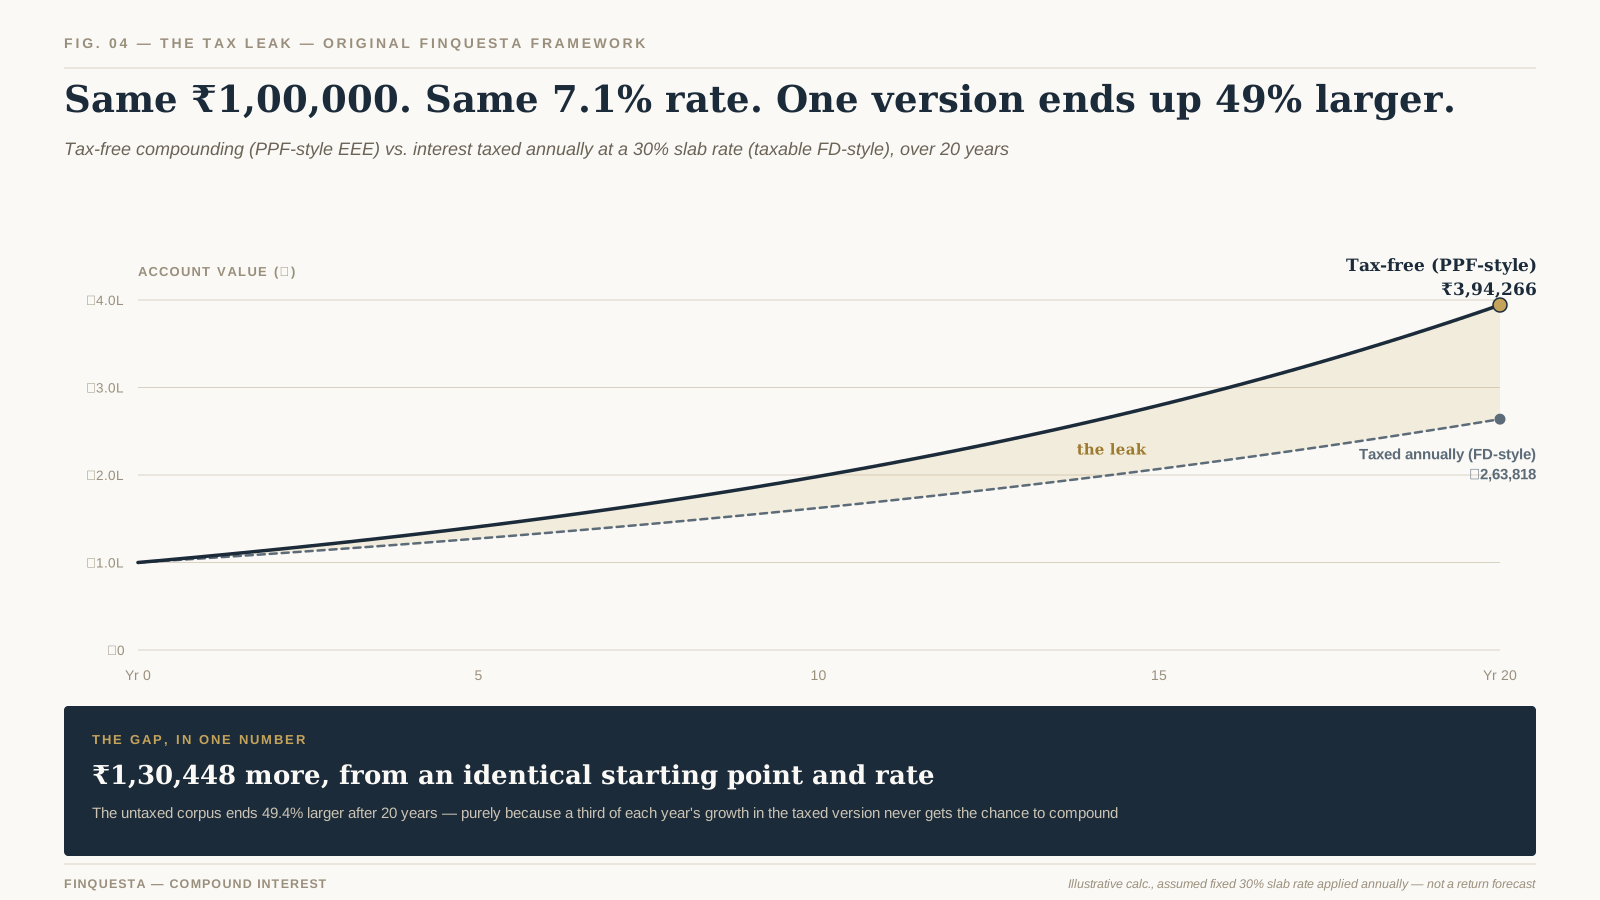
Compare two ₹1,00,000 deposits, both earning an identical 7.1% a year (the current PPF rate — see below), over 20 years. One compounds completely untouched. The other has its interest taxed away annually at a 30% slab rate, the way a taxable fixed deposit’s interest is treated in India, before the balance is allowed to keep growing.

FIG. 04 — The Tax Leak: identical 7.1% rate, tax-free vs. taxed annually at a 30% slab rate (Original Finquesta framework)

 Untaxed (compounds fully)Taxed annually at 30%
Year 5₹1,40,912₹1,27,446
Year 10₹1,98,561₹1,62,425
Year 15₹2,79,796₹2,07,004
Year 20₹3,94,266₹2,63,818

Same starting amount. Same headline rate. A ₹1,30,448 gap after 20 years — the untaxed corpus ends up 49.4% larger — purely because one version keeps compounding on its full interest and the other has a third of each year’s growth quietly removed before it gets the chance to compound.

This is precisely why India’s EEE (exempt-exempt-exempt) instruments — PPF being the clearest example — are structurally different from a taxable fixed deposit paying a similar headline rate. It isn’t only that PPF is government-backed; it’s that a taxable FD’s real, compounding rate is quietly lower than its advertised rate for anyone in a taxable bracket, every single year, while an EEE instrument compounds on its full, undiminished rate for the entire holding period.

Real Returns vs. Nominal Returns: What Inflation Quietly Takes Back

There’s a second leak that works the same way as tax, and it’s just as easy to miss: inflation.

If your investment grows at 8% a year and inflation runs at 5% a year, your money isn’t really compounding at 8% in terms of what it can actually buy — it’s compounding at closer to 3% in real terms (the precise calculation is (1.08/1.05) − 1 ≈ 2.86%, not a simple 8% − 5% subtraction, though the subtraction is a reasonable quick approximation at low rates). This matters most for anything held for decades, since a rate that comfortably beats inflation in year one can quietly stop doing so if inflation rises and the nominal rate doesn’t. A fixed deposit paying 7% during a period when inflation is running at 7% isn’t growing your money in real terms at all — it’s holding it still, before tax is even considered.

Where Compounding Happens in India

Public Provident Fund (PPF)

PPF currently pays 7.1% per annum, reviewed quarterly by the Ministry of Finance and unchanged for the July–September 2026 quarter. It carries EEE status — contributions up to ₹1.5 lakh a year qualify for deduction, the interest is tax-free, and the maturity amount is tax-free too, with no annual tax leak of the kind described above. The trade-off is liquidity: a 15-year lock-in (extendable in 5-year blocks), with only limited partial withdrawal before that — which is exactly why this kind of long-lock-in compounding should sit on top of an emergency fund, not instead of one.

Fixed Deposits (FDs)

FD interest is fully taxable, added to your total income every year on an accrual basis and taxed at your income tax slab rate, regardless of whether you’ve actually withdrawn it. That’s the Tax Leak from the section above, playing out in the most common savings instrument in the country.

ELSS (Equity-Linked Savings Scheme)

ELSS funds combine a Section 80C deduction (up to ₹1.5 lakh, only under the old tax regime) with equity-market exposure and the shortest lock-in of any 80C instrument, at three years. Gains are taxed as equity long-term capital gains under Section 112A: 12.5% on gains above ₹1.25 lakh in a financial year, since ELSS units are typically held well past the 12-month equity LTCG threshold.

The Equity Tax Picture More Broadly

For equity mutual funds and listed shares generally: short-term gains (sold within 12 months) are taxed at 20% under Section 111A; long-term gains (held over 12 months) are taxed at 12.5% above a ₹1.25 lakh annual exemption under Section 112A, with no indexation benefit. Debt mutual funds purchased on or after 1 April 2023 are taxed at your income slab rate regardless of how long you hold them.

Where Compounding Happens Globally

401(k) and Traditional/Roth IRA (United States)

For 2026, the IRS allows up to $24,500 in employee contributions to a 401(k), up from $23,500 in 2025, with an additional $8,000 catch-up contribution available from age 50. The IRA contribution limit for 2026 is $7,500, up from $7,000 in 2025 . A traditional 401(k) or IRA defers tax until withdrawal — money compounds untaxed for decades and is taxed only when it comes out — while a Roth version is taxed going in and compounds completely tax-free thereafter. Either structure avoids the annual Tax Leak described earlier; a standard taxable brokerage account does not.

High-Yield Savings Accounts and CDs

Outside retirement accounts, interest from a savings account or certificate of deposit is generally taxable in the year it’s earned, functioning much like an Indian fixed deposit: fully taxed, annually, at your marginal rate.

Common Mistakes That Quietly Kill Compound Growth

Interrupting the compounding. Withdrawing gains “just this once,” pausing contributions during a market dip, or closing an account early doesn’t just cost you what you withdraw — it resets part of the compounding clock on everything that would have kept building on top of it.

Chasing frequency over rate. As shown above, the difference between monthly and daily compounding is small. The difference between a 6% rate and a 9% rate, compounded identically, is not.

Ignoring the Tax Leak until it’s too late. Choosing a fully taxable instrument over a comparable tax-advantaged one, purely out of familiarity, quietly gives up a meaningful share of total growth — not through any single bad decision, but through 20 or 30 repeated small ones.

Treating the Quiet Decade as proof it isn’t working. This is arguably the single most common reason people abandon long-term plans at exactly the point where abandoning them costs the most.

Letting debt compound while paying only the minimum. Minimum payments are sized to cover most of a period’s interest, not to meaningfully reduce the principal — which is exactly why balances at 30%+ rates can feel permanent even when payments are being made every month.

How to Actually Start This Month

You don’t need a large amount or a complicated plan to put any of this to work. A recurring monthly contribution — a SIP into a mutual fund, a PPF deposit made before the 5th of the month to maximise that month’s interest, or an automatic transfer into a retirement account — does more than a single large, sporadic deposit, because it starts more money compounding sooner rather than later, and if you’re weighing that against investing a bonus or lump sum in one go, the comparison is its own decision. If you’re still deciding where that monthly amount should actually go, that’s a separate decision with its own trade-offs around risk, liquidity, and goals.

Frequently Asked Questions

What is compound interest in simple terms?

It’s interest calculated on your original amount plus all the interest you’ve already earned, rather than on the original amount alone. Each round of interest becomes part of the base for the next round, which is why growth accelerates over time instead of staying flat.

Is compound interest always in my favour?

No — it’s directionally neutral. It works in your favour on savings, deposits, and investments, and against you on any debt you’re carrying, including credit cards and personal loans. The mechanism is identical either way; only the direction changes.

Can I lose money even when compound interest is working for me?

Yes, if the underlying investment is market-linked. Compound interest describes how returns build on themselves over time — it doesn’t guarantee the return itself will be positive in any given year. Fixed-rate instruments like PPF or a bank FD don’t carry this risk; market-linked instruments like equity mutual funds do.

What is the difference between simple interest and compound interest?

Simple interest is calculated only on the original principal, every period, so it grows in a straight line. Compound interest is calculated on the principal plus all previously earned interest, so it grows on an accelerating curve. Over long periods, the gap between the two becomes substantial even at identical rates.

Monthly compounding vs. annual compounding — which is better?

Monthly is mathematically better, but usually only by a few percentage points over long periods — roughly 5–6% more than annual compounding over 20 years at a typical rate, based on the calculation above. It’s worth a slight preference, not a decision-changing one; the interest rate itself matters far more.

How long does it take to double my money with compound interest?

Roughly 72 divided by your annual interest rate, in years — the Rule of 72. At 8%, that’s about 9 years. The shortcut is accurate in the 6–10% range and increasingly understates the real doubling time above about 15%.

Does compound interest apply to SIPs and mutual funds?

Yes, in the form of compound returns rather than compound interest specifically — each year’s gains (or losses) are calculated on the full current value of your holdings, including all prior growth, not just your original contributions. The mechanism is the same idea; the underlying return isn’t fixed or guaranteed the way bank interest is.

Is compound interest income taxable in India?

It depends entirely on the instrument. PPF interest is completely tax-free (EEE status). Fixed deposit interest is fully taxable every year at your income tax slab rate. Equity mutual fund gains are taxed under the capital gains rules described above, not as interest income.

The Bottom Line

Compound interest isn’t a trick, a secret, or a wonder of the world attributed to a physicist who probably never said the line. It’s arithmetic that rewards two things above all else: staying invested through the Quiet Decade, when the results don’t yet look like much, and keeping as much of your growth as possible actually compounding — instead of leaking out annually to tax, sitting idle at a rate that barely beats inflation, or working against you in an unpaid balance somewhere. None of that requires predicting the market. It mostly requires not interrupting a process that was already working.

Disclaimer This article is for informational and educational purposes only and does not constitute financial, investment, tax, or legal advice. Figures, rates, and regulations mentioned are subject to change; please verify current details with official sources (RBI, SEBI, the Income Tax Department, IRS, or a licensed financial advisor) before making financial decisions. Finquesta may earn a commission from affiliate links in this article at no extra cost to you.
Index Funds vs ETFs: Pick the Best Fit in 2026

ETF

An index fund and an ETF are two different vehicles for buying the same thing: a basket of securities built to track a market index, such as the S&P 500 or the Nifty 50. Both are usually low-cost and passively managed. An index mutual fund trades once a day at its end-of-day price and often has a minimum investment. An ETF trades all day like a stock and needs a brokerage or demat account. Both are regulated — by the SEC in the US, by SEBI in India — and both are common holdings inside retirement accounts.

Two colleagues, same starting salary, same decision to start investing this month. One opens an account with a fund company and sets up a recurring $300 purchase into an S&P 500 index fund. The other opens a brokerage account and buys shares of an S&P 500 ETF whenever she remembers to. Five years later, both portfolios have grown by roughly the same amount — because they own, almost exactly, the same underlying stocks. The difference between them was never really about performance. It was about structure: how the fund is built, how it’s taxed, and how it fits into the rest of a saver’s financial life.

That’s the part most comparisons skip. They line up expense ratios side by side and call it a day. The more useful question is: given your account type, your trading habits, and where you live, which structure actually removes more friction from your investing life?

What Is an Index Fund?

An index fund is a mutual fund built with one job: hold the same securities, in roughly the same proportion, as a named market index. If the Nifty 50 rises 1.2% on a given day, a Nifty 50 index fund’s underlying portfolio should rise by close to the same amount, minus a small fee. Nobody is picking stocks. There’s no manager trying to beat the market — the fund’s entire strategy is to become the market, as cheaply as possible.

You buy and sell index fund units directly through the fund company (called an AMC — Asset Management Company — in India) or through a brokerage or retirement platform. Orders placed during the day are all filled at the same price: the fund’s Net Asset Value, or NAV, calculated once after markets close. There’s no haggling over price and no bid-ask spread — you get exactly the NAV, whether you buy at 9 a.m. or 3 p.m.

What Is an ETF, Really?

An ETF (exchange-traded fund) is not, strictly speaking, an investment strategy — it’s a wrapper. “ETF” describes how a fund is structured and traded, not what it holds. Most ETFs happen to be index funds in spirit — built to track something like the S&P 500 or a gold price — but the ETF structure itself is neutral. Actively managed ETFs exist too, though they’re a minority of the market.

What makes an ETF an ETF is that its shares list on a stock exchange and trade continuously during market hours, just like a share of Apple or Reliance Industries. You need a brokerage account (in India, a demat and trading account) to hold one. Its price moves in real time based on supply and demand, though authorized participants — large institutional trading firms — work to keep that price closely aligned with the value of the fund’s underlying holdings.

The Core Difference: A Structure, Not a Strategy

It helps to separate two questions that get blurred together: what does the fund own, and how do you buy and sell it? “Index fund” answers the first question — it describes the strategy (track an index passively). “ETF” answers the second — it describes the wrapper (trade on an exchange, all day, like a stock). A Nifty 50 index fund and a Nifty 50 ETF can hold an almost identical basket of 50 stocks. What differs is entirely about the mechanics of buying, selling, pricing, and — as the next two sections show — taxation.

How They’re Priced and Traded

An index mutual fund is priced once per trading day. Every buy or sell order placed before the fund’s daily cutoff time is filled at that day’s closing NAV — the same price for every investor, regardless of when during the day they placed the order.

An ETF trades continuously from market open to close. Its price can differ, sometimes by a small margin, from the value of the assets it holds — this gap is usually tiny for popular, heavily traded ETFs and wider for thinly traded ones. Because ETFs trade like stocks, buying or selling one usually means paying a bid-ask spread — the small gap between what buyers are offering and what sellers are asking. Popular, high-volume ETFs tend to have narrow spreads; low-volume ETFs can have spreads wide enough to meaningfully eat into a small trade.

index fund

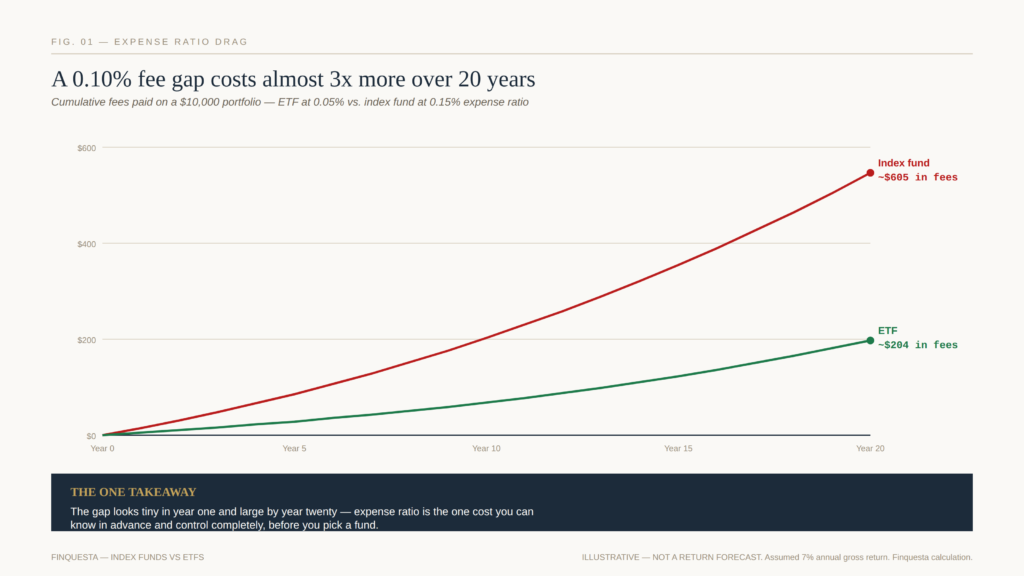
FIG. 01  How a 0.10 percentage-point expense ratio gap compounds over 20 years on a $10,000 portfolio.

Expense Ratios: How Much Does 0.10% Actually Cost You?

On average, ETFs tend to carry slightly lower expense ratios than comparable mutual funds, though the gap has been shrinking for the most popular, heavily traded index products — for widely tracked benchmarks like the S&P 500, the difference between a fund’s ETF share class and its cheapest index-fund share class is often negligible.

The chart above isn’t a real fund’s fee history — it’s a simple compounding calculation, assuming a 7% annual gross return with no other variables changing, comparing a 0.05% expense ratio against a 0.15% one on a $10,000 starting balance. The point isn’t the exact dollar figures; it’s the shape of the curve. A gap that looks trivial in year one — a few dollars — becomes a meaningfully larger sum after two decades of compounding, purely because fees compound too, just in the wrong direction for you.

The practical takeaway: don’t assume the ETF is automatically cheaper. Compare the specific expense ratio of the specific fund you’re considering — published in its fact sheet or scheme information document — against the specific index fund tracking the same benchmark. On core, high-volume index products from the same fund provider, the two are often priced identically.

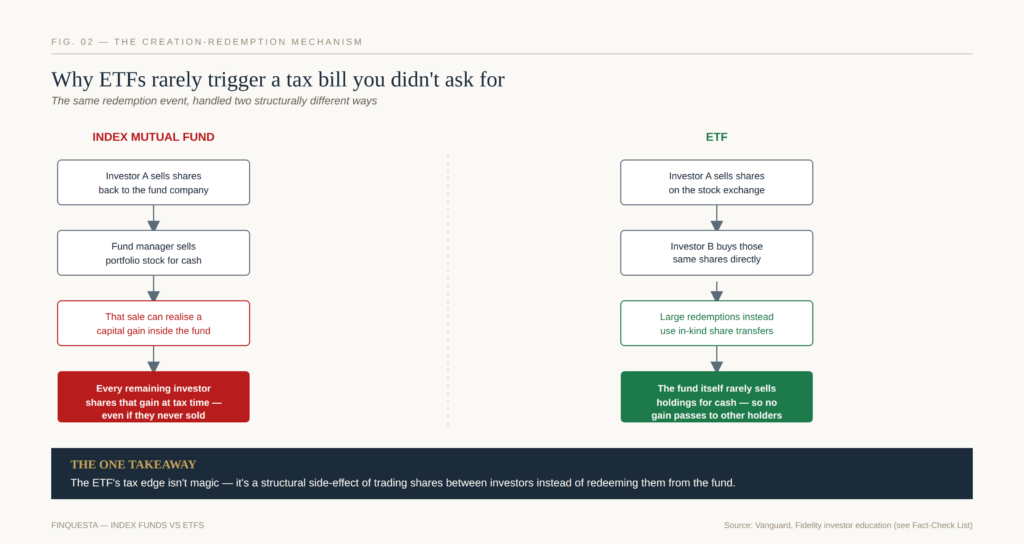
The Creation-Redemption Mechanism: Why ETFs Are Often More Tax-Efficient

This is the single most misunderstood difference between the two structures, and it comes down to a plumbing detail most investors never see.

When an index mutual fund investor redeems units, the fund company may need to sell some of the fund’s underlying holdings to raise the cash to pay that investor out. If those holdings have appreciated, that sale can realize a capital gain — and by law, that gain gets distributed to every investor still holding the fund, whether or not they sold anything themselves that year.

An ETF mostly sidesteps this. Everyday buying and selling happens between investors on the exchange — the fund itself isn’t involved and doesn’t need to sell anything. Large-scale creation and redemption of ETF shares (done by authorized participants, not everyday investors) typically happens through in-kind transfers of securities rather than cash, which under US tax law doesn’t trigger a taxable event for the fund. The practical result: ETFs distribute capital gains to shareholders far less often than comparable mutual funds.

index etf

FIG. 02  The same redemption event routed two structurally different ways — cash-based for a mutual fund, in-kind for an ETF.

This tax advantage matters most in a regular taxable brokerage account. Inside a tax-advantaged account — a 401(k), an IRA, or in India an EPF/NPS-linked structure — capital gains distributions don’t create an immediate tax bill either way, so this entire advantage becomes close to irrelevant.

Tax Treatment in the US: What the IRS Actually Sees

This section applies to United States taxpayers. From the IRS’s perspective, ETFs and mutual funds are taxed under the same basic rules: capital gains and dividend income are both taxable, and long-term capital gains — on assets held more than a year — get preferential rates.

The difference isn’t in the tax rate — it’s in how often a taxable event gets triggered involuntarily. As covered above, ETFs generate fewer unplanned capital gains distributions than comparable index mutual funds, which is what people mean when they call ETFs “more tax-efficient.” It’s a difference in frequency of taxation, not in the rate applied once a gain is realized.

None of this matters inside a 401(k), traditional IRA, or Roth IRA — those accounts already shelter or defer the tax on capital gains and dividends, so the ETF tax advantage has nothing to bite into there.

Tax Treatment in India: STCG, LTCG, and a Surprising Non-Difference

This section applies to Indian taxpayers, under the Income Tax Act as amended by the Union Budget 2024, applicable for FY 2025-26 (AY 2026-27). Rules referenced here should be verified against the current Finance Act before publishing, since capital gains rules can change with each year’s Union Budget.

For equity-oriented funds — where at least 65% of the portfolio sits in Indian equities — an index fund and an equity ETF tracking the same benchmark are taxed identically. Units held 12 months or less are taxed as short-term capital gains at 20%, under Section 111A. Units held longer than 12 months qualify for long-term capital gains treatment at 12.5% under Section 112A, and a financial year’s combined equity long-term gains are untaxed up to a ₹1.25 lakh threshold, with only the amount above that taxed.

This is the coverage gap most India-focused comparisons miss: for a plain-vanilla equity index fund versus an equity ETF tracking the same index, the creation-redemption tax advantage that matters so much in the US barely shows up in an Indian investor’s tax bill, because Indian capital gains tax is based purely on the investor’s own holding period and gain — not on whether the fund distributed gains to other holders along the way. The US-style “tax efficiency” argument for ETFs is weaker in the Indian context than most articles suggest.

Where the two do diverge in India is Securities Transaction Tax (STT), a small levy the seller pays on every exchange-listed trade, including ETF units. Paying STT is also the condition that qualifies a trade for the lower Section 111A/112A rates in the first place. Index fund transactions through an AMC don’t carry STT in the same way, though this is a minor cost relative to the STCG/LTCG rate difference itself.

Debt-oriented, gold, silver, and international funds follow a different, more complex set of rules that changed materially after the Finance (No. 2) Act 2024 — those categories deserve their own dedicated comparison rather than a summary here, since the details (holding periods, Section 50AA applicability) are easy to get wrong and change from year to year.

Minimum Investment and Accessibility

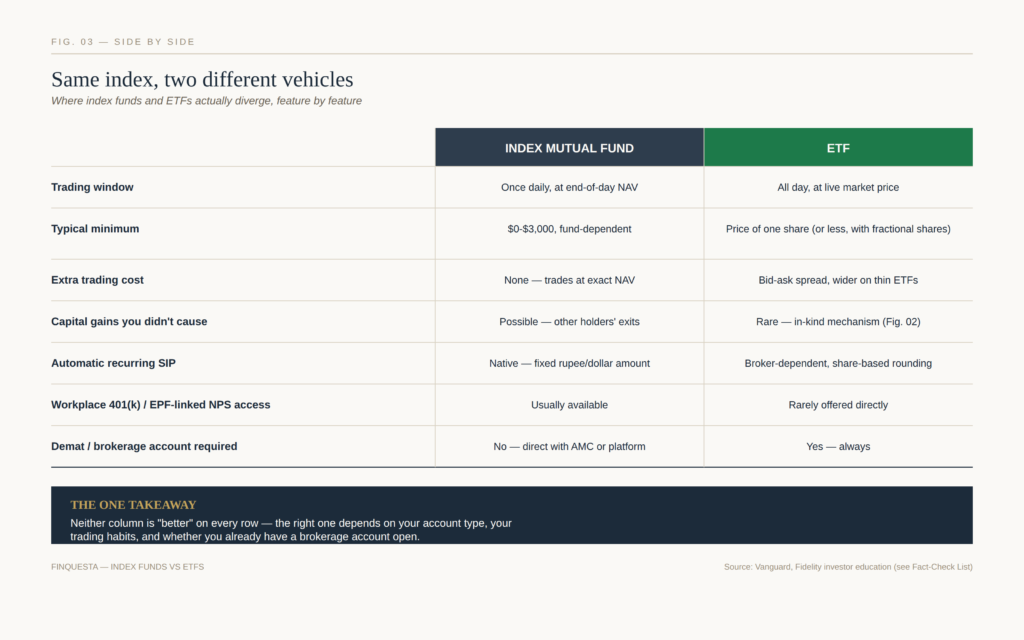
Index mutual funds have historically required a minimum initial investment — sometimes as low as zero at large no-minimum providers, sometimes a few thousand rupees or dollars. An ETF’s floor is usually just the price of a single share, and fractional-share investing — now a standard feature at most major brokers — pushes that floor even lower, putting a high-priced ETF within reach of a modest monthly budget.

In practice, this gap has narrowed. Several large fund providers have dropped their index fund minimums to zero, and fractional-share ETF investing is now common at major brokers. The bigger accessibility question today isn’t the minimum check size — it’s whether you already have a brokerage or demat account open, since an ETF strictly requires one and an index fund, in many cases, doesn’t.

index etf

FIG. 03  A feature-by-feature comparison of index mutual funds and ETFs, from trading windows to retirement-account access.

SIP vs Lump Sum: Which Fits Your Habits

A Systematic Investment Plan (SIP) — or, in the US, an automatic recurring investment — lets you invest a fixed sum on a set schedule without manually placing an order each time. Index mutual funds were built for this. You specify a rupee or dollar amount, and the fund company converts it into however many units (including fractional units) that amount buys at the day’s NAV.

ETFs weren’t originally designed around fixed-amount recurring investing, because you buy whole (or, at some brokers, fractional) shares at a live price, not a fixed rupee amount. Some brokers now offer ETF-based SIPs that handle the share-fraction math automatically, but this feature depends entirely on your specific broker or platform — it isn’t universal the way mutual fund SIPs are.

If your plan is “invest the same amount automatically every month and don’t think about it,” the index fund SIP structure removes more friction. If your plan involves occasional, deliberate purchases at moments you choose, the ETF’s live pricing is a better match for that behavior.

Liquidity and the Spread Trap

Here’s a cost that rarely gets quantified in beginner comparisons: the bid-ask spread. When you buy an ETF, you typically pay slightly more than the last traded price; when you sell, you receive slightly less. For a heavily traded ETF tracking the S&P 500 or the Nifty 50, that gap is usually a fraction of a rupee or cent — immaterial. For a niche or thinly traded ETF, the spread can be wide enough that it quietly cancels out the expense-ratio advantage the ETF was supposed to offer.

Original Finquesta concept: we call this the Spread Trap — the tendency for investors to fixate on an ETF’s lower published expense ratio while ignoring the bid-ask spread on a low-volume fund, a cost that never appears in the fact sheet but shows up every single time you trade.

The fix is simple: before buying any ETF, check its average daily trading volume and its typical bid-ask spread (most brokerage platforms display this). If a fund trades thinly, either the expense ratio savings need to be large enough to justify the spread cost, or the index fund version of the same benchmark is probably the more efficient choice.

The Access Lag: The Friction Nobody Names

Every comparison talks about fees and taxes. Almost none talk about the practical friction of actually executing a purchase — and that friction differs meaningfully between the two structures.

Original Finquesta concept: the Access Lag is the gap between deciding to invest and actually completing that investment. An index fund SIP collapses this gap to zero after setup — money moves automatically, at a fixed amount, without you doing anything each month. An ETF purchase requires you to be logged into a live brokerage account during market hours, check a live price, and place a trade — a small but real behavioral hurdle that, repeated monthly for years, is where a meaningful share of “I meant to invest but didn’t get around to it” actually happens.

This isn’t a reason to avoid ETFs — it’s a reason to be honest about which structure matches your actual behavior, not your intended behavior. If automatic, hands-off investing is what keeps you consistent, the index fund’s built-in automation is doing real work that a slightly lower ETF expense ratio can’t make up for.

index etf

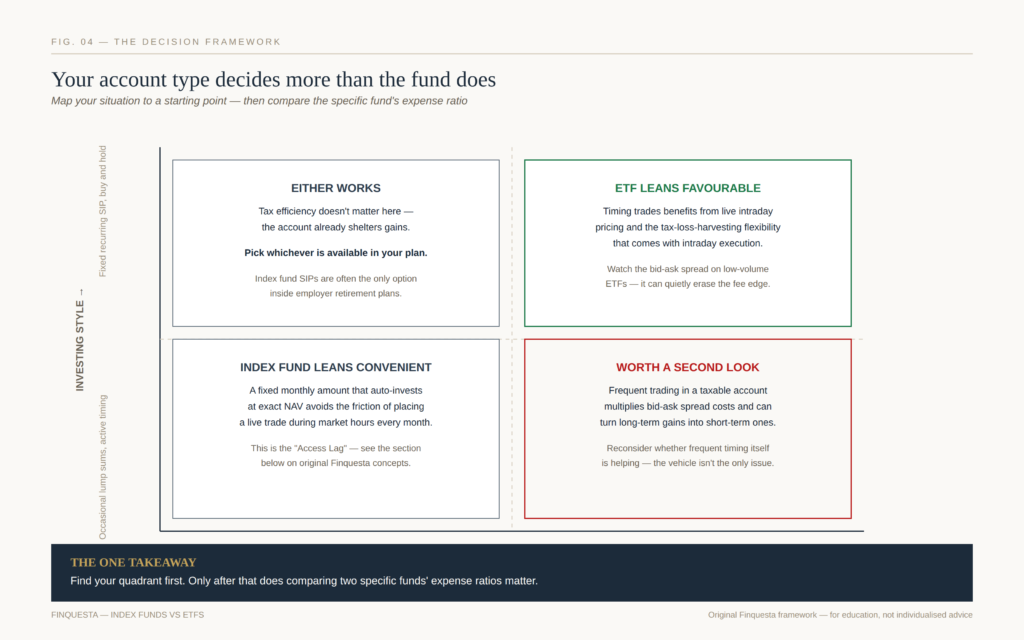
FIG. 04  A simple framework: your account type and investing style narrow the choice before the specific fund’s expense ratio does.

Which Should You Choose? Putting It Together

There’s no universal answer here, and any article that gives you one is skipping the part where your account type and habits matter more than the vehicle. What the evidence above actually supports is a short sequence of questions, in order:

  • Is this money going into a tax-advantaged account (401(k), IRA, EPF/NPS-linked structure)? If so, the ETF tax-efficiency argument mostly disappears — pick whichever is available and matches the benchmark you want.
  • Do you want a fixed amount to auto-invest every month without logging in? The index fund SIP structure is built for that.
  • Are you investing in a regular taxable account and comfortable placing occasional live trades? The ETF’s tax structure and intraday pricing are more likely to work in your favor — provided the specific fund is liquid enough that the bid-ask spread doesn’t erase the benefit.
  • Does your workplace retirement plan or platform only offer one of the two? That access constraint usually overrides every other consideration.

This is a framework for evaluating the two structures, not a recommendation of any specific fund, provider, or index — the right choice depends on products, costs, and rules that can change, and that only you (ideally with a licensed advisor) can evaluate for your specific situation.

Common Mistakes Investors Make When Choosing

  • Assuming the ETF is automatically cheaper without checking the specific expense ratio of the specific fund.
  • Buying a thinly traded ETF and losing the fee advantage to the bid-ask spread (the Spread Trap).
  • Treating the US tax-efficiency argument as if it applies the same way to Indian equity funds, when Indian capital gains tax depends on your own holding period rather than on other investors’ redemptions.
  • Choosing based on fees or taxes alone, while ignoring whether the Access Lag will realistically derail a recurring investing habit.
  • Forgetting that inside a tax-advantaged retirement account, most of the ETF-versus-index-fund tax discussion is moot.

Frequently Asked Questions

What is the difference between an index fund and an ETF in simple terms?

An index fund is a strategy — hold a basket of securities to track a market index. An ETF is a structure — a fund whose shares trade on a stock exchange all day, like a stock. Most ETFs happen to be index funds, but the two words are answering different questions: what the fund owns, versus how you buy and sell it.

Is an ETF safe?

An ETF tracking a broad, well-known index carries the same underlying market risk as an index mutual fund tracking the same benchmark — neither is inherently safer, since they can hold nearly identical portfolios. The structure itself (exchange-traded shares, regulated by the SEC in the US or SEBI in India) is not a source of additional risk for a standard, broad-market index ETF.

Can I lose money in an index fund or ETF?

Yes. Both track a market index, and if that index falls, the fund’s value falls with it. Neither structure protects you from market-wide declines — that protection doesn’t come from choosing index fund versus ETF, it comes from your asset allocation and time horizon.

What is the difference between an index fund and an ETF for tax purposes?

In the US, ETFs typically distribute capital gains to shareholders less often than comparable index mutual funds — a byproduct of the in-kind share-transfer process described above, rather than anything about the tax rate itself. In India, for equity-oriented funds, the two are taxed almost identically under Sections 111A and 112A, since Indian capital gains tax depends on your own holding period rather than on fund-level redemption activity.

Index fund vs ETF — which is better for a beginner?

For a beginner setting up automatic monthly contributions with no interest in watching live prices, the index fund SIP structure typically removes more friction. For a beginner who already has a brokerage account and wants the flexibility of intraday pricing, a liquid, broad-market ETF is an equally reasonable starting point. Neither is objectively “better” — see the Decision Framework above.

How many index funds or ETFs should I own?

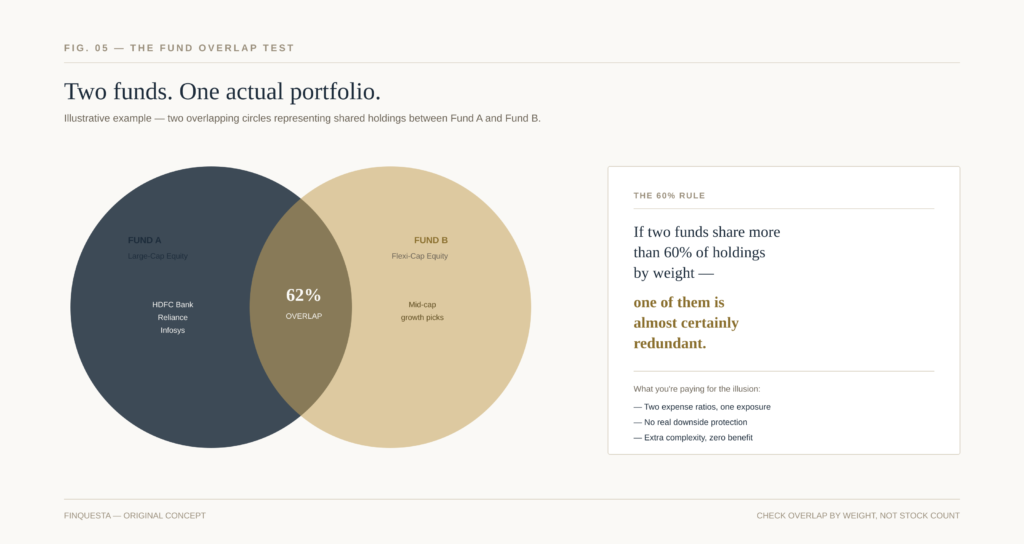
There’s no fixed number that applies to everyone, and this is a portfolio construction question rather than an index-fund-versus-ETF question. Many long-term investors build a portfolio around a small number of broad, low-cost, non-overlapping index funds or ETFs rather than accumulating many overlapping ones — but the right number depends on your goals, risk tolerance, and account structure.

Do ETFs have a minimum investment?

Generally no minimum beyond what one share costs, and fractional-share investing at most major brokers pushes that floor lower still. Index mutual funds vary by provider — some have dropped their minimums to zero, others still require an initial minimum investment ranging from a small amount to several thousand rupees or dollars.

What is the difference between an index fund and an actively managed fund?

This is a different comparison than index fund vs ETF. An index fund (whether structured as a mutual fund or an ETF) tries to match a benchmark as closely as possible at low cost. An actively managed fund has a manager making buy/sell decisions attempting to beat a benchmark, typically at a higher expense ratio. Both index mutual funds and index ETFs are, by definition, passive; the active-vs-passive question is a separate axis from the mutual-fund-vs-ETF question covered in this article.

Disclaimer

This article is for informational and educational purposes only and does not constitute financial, investment, tax, or legal advice. Figures, rates, and regulations mentioned are subject to change; please verify current details with official sources (RBI, SEBI, the Income Tax Department, IRS, or a licensed financial advisor) before making financial decisions. Finquesta may earn a commission from affiliate links in this article at no extra cost to you.
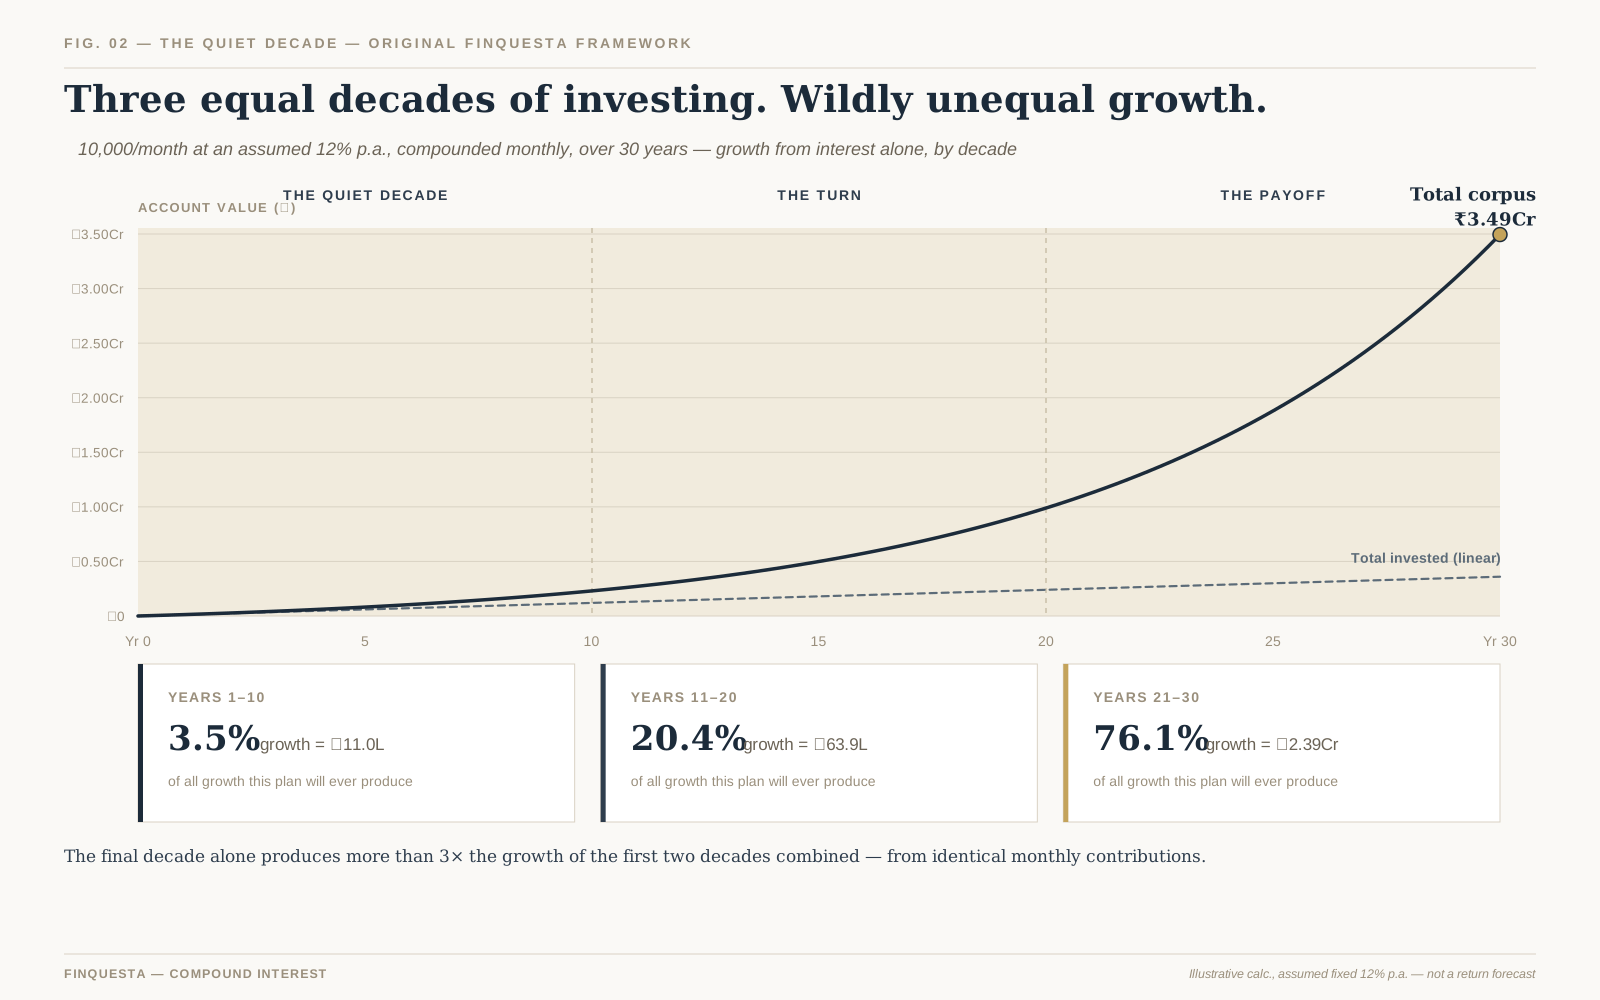
SIP vs Lump Sum Investing: Which One Is the Best? [2026]

sip vs lump sum

WHAT IS SIP VS LUMP SUM?

Meera’s company pays her annual bonus every April. Last year it was ₹4.2 lakh, and it sat in her savings account for nineteen days before she did anything with it. She already knew she wanted it in equity mutual funds. What she didn’t know was whether to put it all in on a Monday morning, or split it into pieces and feed it in over the year.

That’s the SIP vs lump sum question, and almost every Indian investor runs into it eventually — not as an abstract choice between two investing “philosophies,” but as a real decision about real money sitting in a real bank account. A bonus. A fixed deposit that just matured. An inheritance. Proceeds from a property sale. Money that already exists, right now, waiting on a decision.

Here’s the honest answer to SIP vs lump sum: they aren’t competing philosophies. They’re answers to two different questions. Most of what’s written about this topic answers only the first one.

What is a SIP, exactly?

A Systematic Investment Plan is a standing instruction to your mutual fund to buy units worth a fixed amount — say ₹10,000 — on a fixed date every month, debited automatically from your bank account. You’re not deciding, each month, whether to invest. You decided once, and the SIP just runs.

SIPs can start as low as ₹500 a month at most fund houses, and AMFI’s “Chhoti SIP” initiative has pushed some schemes down to ₹250 — low enough that the barrier to starting is essentially zero. This is why SIP has become the default entry point for salaried investors: it matches how income actually arrives, in monthly instalments, not in one large sum.

It’s also why SIP is the engine behind India’s mutual fund growth. Monthly SIP contributions have run above ₹30,000 crore for months, with SIP assets now above ₹17 lakh crore — roughly one in every five rupees the Indian mutual fund industry manages. That scale exists because SIP removes the two hardest parts of investing: deciding when, and remembering to.

What is a lump sum investment, exactly?

A lump sum investment is the opposite motion: one transaction, the full amount, done. If Meera puts her entire ₹4.2 lakh bonus into a fund on a single day, that’s a lump sum. There’s no schedule, no recurring debit, no discipline required after the fact — the discipline was required before, in deciding to actually do it rather than let the money sit.

Most funds accept lump sum investments starting at ₹1,000, though ₹5,000 is a more common practical floor at many AMCs. Lump sum suits money that already exists as a single block: a bonus, a maturity payout, an inheritance, sale proceeds. It’s not really a “strategy” chosen from a menu — it’s usually the only sensible way to deploy money that arrived all at once and has nowhere productive to sit in the meantime.

SIP vs lump sum: what actually happens to your money

Strip away the marketing language, and the mechanical difference between SIP and lump sum comes down to one thing: how many different prices your money pays for the same fund.With a lump sum, every rupee buys units at a single NAV, on a single day. If that day happens to be a local peak, all your capital bought in expensive.

If it happens to be a dip, all your capital bought in cheap. You don’t find out which for months or years.With a SIP, your capital is split across many purchase dates, each at that month’s NAV. Some instalments buy in high, some buy in low, and your effective cost becomes an average of all of them — a number no single instalment actually paid, but one your total holding reflects. This is the entire mechanical basis of what gets called “rupee cost averaging,” and it’s worth being precise about what it does and doesn’t do, because most explanations aren’t.

There’s a second, less-discussed difference: how the two approaches are taxed. In a lump sum, the whole investment shares one purchase date and one holding period. In a SIP, every instalment is legally a separate investment with its own purchase date — which matters enormously when you eventually redeem (more on this in the tax section below).

sip vs lump sum

FIG. 01 — SIP vs Lump Sum: same goal, two different entry mechanics

Rupee cost averaging: what it actually does — and doesn’t do

Rupee cost averaging gets described, almost everywhere, as a way to “reduce risk” in a SIP. That’s not quite right, and the imprecision matters.

Averaging doesn’t remove market risk. It restructures when that risk lands. A lump sum takes on all its price risk on day one and is done with it.

A SIP spreads that same risk across the deployment period — which means a SIP investor is still exposed to unfavourable prices, just in smaller, more frequent doses instead of one large one.

If the market only ever goes up during your SIP’s deployment window, averaging actively costs you money compared to a lump sum, because your later instalments buy fewer units at higher prices than your capital would have bought on day one.

Averaging helps only when there’s a meaningful dip somewhere inside the window you’re investing through — and there’s no way to know in advance whether that dip is coming.

What rupee cost averaging reliably does is something different and arguably more valuable: it removes the need to pick a date. A lump sum investor has to choose one entry point and live with it. A SIP investor never has to choose — the schedule chooses for them, every month, regardless of what the market did last week. That’s not risk reduction in the statistical sense. It’s decision removal, and for most people, that turns out to matter more than the maths.

What the research actually shows about SIP vs lump sum returns

This is the part most SIP vs lump sum articles skip, because the honest answer is uncomfortable: on average, lump sum wins more often than SIP does.

Vanguard’s research group has studied this question repeatedly, comparing a lump sum investment against spreading the same capital out over time, across the US, UK, and Australian markets, using rolling one-year windows going back to 1976. The result has been consistent across studies: the lump sum approach came out ahead somewhere between roughly 62% and 74% of the time, commonly summarised as “about two-thirds.”

The reason isn’t complicated — equity markets rise more often than they fall over any given year, so capital that’s fully invested from day one has more time exposed to that upward drift than capital still waiting on the sidelines to be deployed.It gets more interesting at the extremes.

Even at the 25th percentile of outcomes — a below-average result — lump sum investing still tends to beat the averaged alternative. It’s only in roughly the worst 5% of outcomes that spreading the investment out comes out ahead, and even then the margin is modest. In the best outcomes, lump sum’s lead widens further, because it had more capital exposed to the rally for longer.

None of this research is India-specific — it’s US, UK, and Australian data, and Indian equity markets have their own volatility and return characteristics that a rigorous Nifty-specific version of this study would need to account for But the underlying logic — markets trend upward more often than not, and time in the market is worth more than the price you paid to get in — doesn’t depend on which country’s index you’re using.

There’s a second finding buried in the same research that rarely makes it into the SIP vs lump sum debate, and it matters more than the headline number: the gap between lump sum and SIP is small. The gap between either of them and doing nothing — leaving the money in a savings account while you wait for a “better time” — is enormous. The real risk in this decision was never SIP versus lump sum. It’s the third, unstated option: neither.

So why does almost everyone still recommend SIP?

If lump sum wins more often on paper, why does nearly every advisor, every fund house, and every finance article still push SIP as the default? Because the research above measures a different thing than what actually determines most people’s outcomes.

It measures returns assuming the investor sits still and does nothing else. It doesn’t measure what investors actually do when a lump sum investment drops 12% in the first month. Some hold. A meaningful number panic and exit — locking in a loss that a SIP investor, who’d only deployed a fraction of their capital at that point, would barely have felt. The mathematically optimal strategy that you abandon halfway through is worth less than the slightly-less-optimal strategy you actually complete.

This is the real argument for SIP, and it has nothing to do with rupee cost averaging: it’s about behaviour, not maths. A SIP is a pre-commitment device. It takes the decision to invest — which most people get wrong precisely at the moments it matters most, panicking at lows and getting greedy at highs — and replaces it with a standing instruction that doesn’t check the news before it executes. You don’t have to be disciplined every month. You only have to be disciplined once, at setup.

There’s a related, quieter cost to lump sum investing that doesn’t show up in a returns table: sequencing regret. An investor who puts ₹5 lakh in and watches it fall to ₹4.4 lakh within weeks experiences that loss as a single, sharp, attributable event — “I invested badly.” A SIP investor who’s only deployed one-twelfth of the same capital when the same dip happens experiences almost nothing, because most of the capital hadn’t arrived yet. Both investors may end up at the same place in three years. Only one of them had to survive the emotional experience of getting there.

The Stock-Flow Test: deciding SIP vs lump sum without guessing

Most SIP vs lump sum advice collapses into “it depends on your risk appetite,” which is true and almost useless. Here’s a sharper way to actually decide, built on two questions rather than one — an original Finquesta framework.

Question one: is this money a stock, or a flow? In economics, a stock is an amount that exists at a single point in time — money already sitting in your account. A flow is an amount that arrives over a period — a salary, paid in instalments. A bonus, an inheritance, or maturity proceeds are stock: they already exist, in full, right now. Monthly savings from your salary are a flow: they don’t exist yet next month, only the intention to save does.

Question two: how confident are you, right now, that valuations aren’t stretched? Not a market-timing prediction — just an honest gut check on whether you’d feel fine deploying this money today, versus feeling nervous about the level markets are at.

Cross the two questions and four situations fall out, each with a different honest answer:

Flow money, high conviction — this is the default case for most salaried investors. A plain SIP is correct. There’s no lump sum decision to make because the money doesn’t exist yet as a lump sum. – Flow money, low conviction — still SIP. A SIP already solves the anxiety, since you’re never deploying more than one month’s contribution at any single price. – Stock money, high conviction — deploy as a lump sum. This is the case the Vanguard research above speaks to most directly: money that already exists, going into a market you’re not nervous about, should go in now rather than be drip-fed in over a year for no statistical benefit. – Stock money, low conviction — this is the quadrant almost nobody explains properly, and it’s exactly Meera’s situation with her bonus. The honest tools here aren’t “SIP the whole thing manually” or “wait for a dip that may not come.” It’s the hybrid covered next.

The-Stock-Flow-Test

FIG. 03 — The Stock-Flow Test: an original Finquesta decision framework

STP: the SIP vs lump sum hybrid nobody explains properly

Most SIP vs lump sum comparisons present the choice as binary and stop there. A Systematic Transfer Plan moves a fixed amount automatically from one mutual fund scheme into another, at regular intervals, within the same fund house. In practice, it’s almost always used the same way: park a lump sum in a liquid or debt fund, then set up an STP that shifts a fixed slice of it into an equity fund every month.

This is the actual answer for the “stock money, low conviction” quadrant above — and it’s a materially better answer than doing a manual SIP with a lump sum sitting idle in a savings account, for one simple reason: the undeployed portion keeps earning a return the whole time it’s waiting, instead of earning nothing. If Meera parks her ₹4.2 lakh bonus in a liquid fund and runs a 12-month STP into an equity fund, the ₹3.85 lakh still waiting in month two is quietly earning a liquid-fund return, not sitting flat in a savings account.

SEBI requires a minimum of six transfers to set up an STP, and it only works between two schemes of the same AMC — you can’t STP from one fund house’s liquid fund into a different fund house’s equity fund. There are three common structures: a fixed STP transfers the same amount each time; a flexi STP lets the transferred amount vary with market conditions; a capital appreciation STP transfers only the gains earned in the source fund, leaving the original capital untouched. For most first-time users, fixed STP is the simplest and most predictable.

One detail that trips people up: every STP instalment is legally a redemption from the source fund, which means it’s a taxable event, not a free internal transfer. If the source is a debt or liquid fund, the gain on each transfer is usually small and taxed at your slab rate — real, but rarely significant over a matter of months. If you’re STP-ing out of an equity fund for any reason, ordinary equity capital gains rules apply to each transfer.

SIP vs lump sum taxation in India: what changed, and what’s changing again

Tax treatment is identical between SIP and lump sum in one sense, and meaningfully different in another — and almost no article distinguishes the two clearly.

The rates are the same, whichever way you invest. For equity-oriented mutual funds (funds holding at least 65% in domestic equities), gains on units held over 12 months are long-term capital gains (LTCG), taxed at 12.5%, with the first ₹1.25 lakh of such gains in a financial year exempt. Gains on units held 12 months or less are short-term capital gains (STCG), taxed at a flat 20%. These rates have applied since 23 July 2024, and Union Budgets in both 2025 and 2026 left them unchanged.

What’s genuinely different is the holding period, and this is where SIP investors get caught out. In a lump sum, the entire investment has one purchase date, so the whole holding crosses into LTCG territory on the same day. In a SIP, every single instalment is treated by law as its own separate purchase, with its own 12-month clock starting from its own date. If you started a SIP twelve months ago and redeem the full holding today, only your very first instalment has actually crossed the 12-month LTCG line — the other eleven are still short-term, and your redemption will generate a mix of STCG and LTCG in the same transaction, calculated instalment by instalment, generally on a first-in-first-out basis. This is rarely explained clearly, and it means a SIP investor closing a holding needs to check the age of each instalment, not just the age of the SIP itself.

A second layer applies specifically to tax-saving investors. ELSS (Equity Linked Savings Scheme) funds carry a mandatory three-year lock-in — the shortest among Section 80C options — and qualify for a deduction of up to ₹1.5 lakh, but only under the old tax regime; the new tax regime, which has been the default since FY 2023-24, does not permit this deduction at all. Because of the lock-in, every ELSS redemption is automatically LTCG — an ELSS unit can never legally be sold early enough to trigger STCG.

There’s a bigger, less-discussed shift sitting underneath all of this. The Income Tax Act, 1961 was repealed and replaced by the Income Tax Act, 2025, effective 1 April 2026 — meaning income earned from that date onward, including gains on investments made or redeemed today, falls under the new Act, not the old one. The concepts of “Previous Year” and “Assessment Year” have been replaced by a single “Tax Year,” and the section numbers investors are used to citing have been renumbered. Section 80C, familiar to every ELSS investor, is now Section 123. The equity capital gains provisions have moved too: short-term gains under the old Section 111A are now under Section 196, and long-term gains under the old Section 112A are now under Section 198, each carrying forward the same 20% and 12.5% rates. Crucially, the tax *rates and deduction amounts themselves have not changed* — only the numbering and terminology have. Anyone filing a return for income earned before 1 April 2026 still uses the old Act’s section numbers; anyone dealing with gains from after that date is now working under the new one.

SIP vs lump sum: a worked example with ₹6 lakh

Numbers make the averaging mechanic concrete in a way explanations can’t. The following is a constructed, illustrative example only — not a return forecast, not based on any real fund’s actual NAV history.

Assumed path: a fund’s NAV moves, hypothetically, from 100 to 96, 90, 85, 88, 92, 87, 95, 102, 108, 113, and finally 118 over twelve months — a meaningful dip in the first third of the year, followed by a recovery that finishes above where it started. Assumed annual return: roughly +18% start-to-finish.  

Lump sum: ₹6,00,000 invested on day one at NAV 100 buys 6,000 units. At the final NAV of 118, that holding is worth ₹7,08,000 — a gain of ₹1,08,000.

SIP: ₹50,000 invested at the start of each month, at that month’s NAV, buys a different unit count each time — more units in the months NAV is low, fewer when it’s high. Across the twelve instalments, this SIP accumulates approximately 6,197 units, at an average cost of roughly ₹96.83 per unit — below both the starting and ending NAV. At the final NAV of 118, that holding is worth approximately ₹7,31,208, a gain of about ₹1,31,208, on the same ₹6,00,000 total invested.

In this specific illustration, SIP comes out ahead — but only because the assumed path includes a meaningful dip inside the deployment window, which is exactly the condition under which averaging helps. Run the identical ₹50,000-a-month SIP through a market that rises smoothly and continuously instead of dipping first, and lump sum wins clearly, for the reason covered earlier: the SIP would spend most of the year buying at progressively higher prices while the lump sum sat fully invested from day one. Neither path is “the normal case” — that’s the entire point of the research above. This example demonstrates the mechanic, not a guaranteed outcome.

FIG. 02 — Illustrative entry price comparison (hypothetical data, not a return forecast)

Common SIP vs lump sum mistakes

On the SIP side: starting one, then stopping it the first time markets fall — which defeats the entire purpose, since the low-NAV months are the ones doing the most work for the average cost. Also common: treating SIP as something that only applies to fresh salary savings, and manually “SIP-ing” a lump sum into a savings account in pieces rather than using an STP, which leaves the undeployed balance earning nothing while it waits.

On the lump sum side: deploying the entire amount without an emergency fund in place first, so a near-term cash need forces an untimely redemption. Also common: treating a single bad entry point as proof the strategy failed, when a bad entry point is a risk lump sum always carried — it just hadn’t been felt yet.

On both sides: waiting for “the right moment” to start at all. That third option — neither SIP nor lump sum, just delay — is the one the research consistently shows costing the most. Whichever way the SIP vs lump sum decision goes, it should be a decision, made on purpose, not a default reached by not deciding.

Frequently asked questions

SIP vs lump sum: which is better?

Neither is better in every situation. Historical research shows lump sum outperforming on average, because markets rise more often than they fall. But SIP wins on behaviour: it’s easier to stick with, and a plan you complete beats a better plan you abandon. Use the Stock-Flow Test above to match the method to where your money is actually coming from.

What is the minimum amount for SIP vs lump sum investing?

Most SIPs can start from ₹500 a month, with some schemes offering ₹250 under AMFI’s Chhoti SIP option. Lump sum investments typically need at least ₹1,000, though ₹5,000 is a common practical floor at many fund houses.  

Can I lose money investing a lump sum in mutual funds?

Yes. A lump sum takes on its full market-price risk on a single day, so if that day turns out to be a local high, the entire investment starts underwater until the market recovers. This is a real risk, not a hypothetical one, and it’s the main trade-off against SIP’s more gradual entry.

Is SIP safe during a market crash?

SIP doesn’t prevent losses during a crash — your existing units still fall in value along with the market. What it does is let you keep buying at lower prices during the crash, which improves your average cost if you continue rather than pause. Stopping a SIP during a crash is one of the most common mistakes investors make, for exactly this reason.

What is the difference between SIP and STP?

A SIP moves new money from outside the mutual fund system — your bank account — into a fund, on a schedule. An STP moves money that’s already inside the mutual fund system, from one scheme to another within the same fund house. SIP is for income you haven’t received yet; STP is for a lump sum you already have but want to deploy gradually.

Should I invest my bonus or inheritance as a lump sum or SIP?

Run it through the Stock-Flow Test above. Bonuses and inheritances are “stock” money — they already exist. If you’re genuinely comfortable with current valuations, a lump sum is the historically stronger choice. If you’re not, an STP from a liquid fund into equity is usually a better-designed answer than either a lump sum you’re anxious about or a manually staggered SIP that leaves cash idle.

Does rupee cost averaging guarantee higher returns?

No. It guarantees a different entry price than a lump sum’s single price — not necessarily a better one. Averaging helps specifically when there’s a meaningful dip during your deployment window; it costs you, relative to lump sum, when the market simply rises throughout that same window. Its real, consistent benefit is behavioural, not mathematical: it removes the need to pick a date.

Is SIP the same as dollar-cost averaging in the US?

Mechanically, yes — both involve investing a fixed amount at regular intervals rather than all at once. The research on dollar-cost averaging versus lump sum investing in the US and other developed markets is where much of the “lump sum wins more often” evidence in this article comes from. The core logic — markets rise more often than they fall, so time in the market usually beats a staggered entry — applies to Indian equity markets for the same structural reason, even though a rigorously India-specific version of the study is something worth seeking out directly.

Disclaimer

This article is for informational and educational purposes only and does not constitute financial, investment, tax, or legal advice. Figures, rates, and regulations mentioned are subject to change; please verify current details with official sources (RBI, SEBI, the Income Tax Department, IRS, or a licensed financial advisor) before making financial decisions. Finquesta may earn a commission from affiliate links in this article at no extra cost to you.
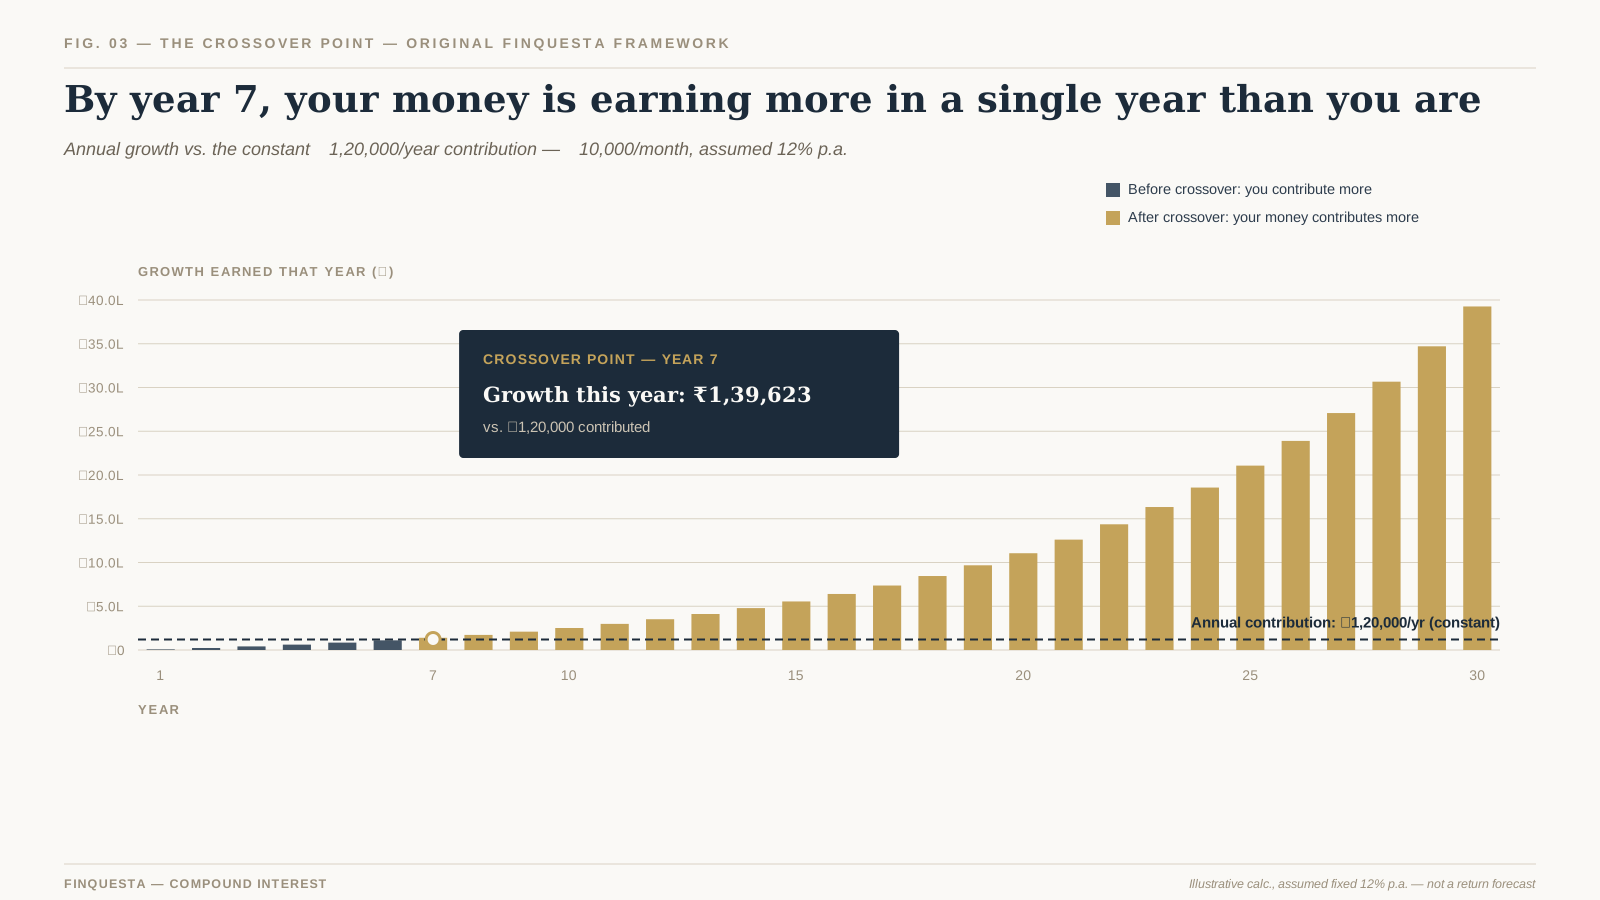
What Is a Mutual Fund? What Most Beginners Get Wrong (2026)

what is a mutual fund
What is a mutual fund, and how does it actually work? This guide covers the mechanics, how to invest in India and the US, types of funds, NAV, SIP vs lump sum, XIRR, costs, tax, and 8 original concepts — written for any reader, from first-timer to retirement planner.
What is a mutual fund — the answer in 90 words Think of a mutual fund as a shared investment account for thousands of strangers who never meet. Each contributor puts in their amount, a professional fund manager deploys the combined pool across dozens or hundreds of assets, and every investor’s return tracks the portfolio in proportion to what they put in.   You own units. Units have a daily price called NAV. You can invest from Rs 500 per month via SIP in India, or from $1 via most major US platforms. Your money is regulated — SEBI in India, SEC in the US — but not guaranteed. Markets move, and so does your NAV.

How a mutual fund actually works — the plumbing most guides skip

Most people grasp the concept in five minutes. The mechanics beneath it take a bit longer — and they matter when things don’t behave as expected.

  1. Your instruction goes to the AMC: Your buy or sell order lands with the Asset Management Company — the SEBI-registered entity that manages the fund. The exact time your money clears matters more than the time you placed the order. This is covered in the NAV cut-off section below.
  2. Your money enters a ring-fenced trust: In India, mutual funds are constituted as trusts under the Indian Trusts Act, 1882. A trustee — not the AMC — holds your money in legal custody. SEBI (India) and the SEC (US) regulate every aspect of how the fund operates. The trust structure means your investment is legally separated from the AMC’s own finances. If the fund house closes tomorrow, the pooled assets belong to unit holders, not to the company’s creditors. That is a meaningful structural protection that most investors never think about until they need it.
  3. The manager or algorithm invests the pool: Active funds: a human fund manager and research team select specific securities, aiming to beat a benchmark. Passive funds: an algorithm mirrors an index — Nifty 50, Sensex, S&P 500 — mechanically, with no subjective judgment. No human can underperform relative to their own conviction when they have no conviction to express.
  4. NAV is computed after markets close: Every business day, the fund totals the current market value of all its holdings — a process called marking to market — subtracts liabilities, and divides by total units outstanding. AMFI publishes the figure by 11 PM. That number is the price at which your order for that day will be settled.
  5. Redemption settles in 1-3 business days: Submit a redemption request, units cancel at that day’s NAV (cut-off rules apply — see below), money reaches your bank account within 1 business day for liquid funds and 2-3 days for most equity and debt funds.

Why the trust structure matters more than most people realise: The Franklin Templeton India 2020 episode — when six debt schemes were wound up due to liquidity stress — is instructive. Investors eventually got their money back because the underlying bond assets belonged to them inside the trust, not to Franklin Templeton as a corporate entity. The winding-up process was painful and slow, but the legal protection held. That would not have been the case with an unregulated investment scheme.

what is a mutual fund

Key terms — decoded without jargon

Every term you will encounter, explained in one clear clause:

The three formulas that actually matter

NAV calculation

Computed daily, published by 11 PM on AMFI:

NAV = (Total Market Value of Assets − Liabilities) ÷ Units Outstanding

Example: Fund holds stocks worth Rs 10 crore. Liabilities (accrued fees, pending redemptions): Rs 10 lakh. Units outstanding: 9 lakh.

NAV = (Rs 10,00,00,000 − Rs 10,00,000) ÷ 9,00,000 = Rs 110 per unit

You invest Rs 11,000. You get 100 units at Rs 110. A year later, NAV = Rs 135. Your 100 units = Rs 13,500. Return: 22.7%.

Lump sum compounding

Future Value = P × (1 + r)ⁿ

P = amount invested   ·   r = annual return rate   ·   n = years

Illustrative lump sum example
Rs 1,00,000 invested at a hypothetical steady 12% per annum:   

Year 5:   Rs 1,00,000 × (1.12)^5  = approx. Rs 1,76,234    Year 10:  Rs 1,00,000 × (1.12)^10 = approx. Rs 3,10,585    Year 20:  Rs 1,00,000 × (1.12)^20 = approx. Rs 9,64,629  

The jump from year 10 to year 20 more than triples the
value again — on the same original rupee.
Not because the rate changed, but because the exponent compounded on a larger base.
Time is the variable nobody can buy more of after the fact.  

SIP future value

FV = P × [((1 + r)ⁿ − 1) ÷ r] × (1 + r)

P = monthly SIP   ·   r = monthly return (annual ÷ 12)   ·   n = total months

Illustrative SIP example
Rs 5,000 per month for 15 years at 12% per annum (hypothetical):   
r = 12%/12 = 1% = 0.01, 
n = 180 months   
FV = 5,000 × [((1.01)^180 − 1) ÷ 0.01] × 1.01 ≈ Rs 25.2 lakh   
Total invested: Rs 9 lakh   |   Growth from returns: ≈ Rs 16.2 lakh  

XIRR vs CAGR — the return number that most platforms don’t explain

This is the single most practically useful thing missing from most Indian beginner guides. The return percentage shown on your investment app is either CAGR or XIRR. They are not the same number, and using the wrong one for the wrong type of investment gives you a fundamentally misleading picture of your actual performance.

 CAGRXIRR
Full nameCompound Annual Growth RateExtended Internal Rate of Return
Right forSingle lump sum, held without additions or withdrawalsSIPs, multiple investments, irregular redemptions
What it modelsOne starting amount, one ending value, straight compoundingEvery individual cash flow with its exact date and rupee amount
Why it fails for SIPsEach monthly SIP instalment was held for a different length of time. CAGR ignores this completely.Accounts for timing of every cash flow — gives the true annualised return of the entire SIP history
How to calculate(End Value ÷ Start Value)^(1/n) − 1No simple formula. Use Excel XIRR() function or your investment platform
What to demand from your appFor lump sum: CAGR is correctFor SIP: insist on XIRR. ‘Absolute return’ (e.g. ‘87% total gain’) is not comparable across different durations

The test: Open your platform and find your SIP return. If it shows a % without saying CAGR or XIRR, call the helpline and ask which method is being used. If they say ‘absolute return’, that number cannot be meaningfully compared to anything — not the index, not a friend’s portfolio, not a fixed deposit rate.

The NAV cut-off clock — which day’s price you actually get

Almost never covered in beginner guides, even though it directly affects the price of every transaction you make. You do not automatically get the NAV of the day you clicked ‘Invest’.

How the NAV cut-off works — India (SEBI rules)
The applicable NAV depends on WHEN your money is credited to the AMC’s account — not when you tapped ‘Buy’.  

For equity and most debt funds (excluding liquid and overnight):   
Funds credited to AMC before 3:00 PM on a business day  =  that day’s closing NAV
    Funds credited after 3:00 PM =  next business day’s NAV  

A real scenario:   
You place a buy order at 2:50 PM Monday. Your bank processes the debit at 3:08 PM. You receive Tuesday’s NAV.
If NAV rose on Monday night, you pay more than you expected.  

SIP date tip:
Bank transfers often process slowly on the 1st, 31st, or dates adjacent to public holidays.   
Set your SIP date between the 5th and 25th of the month to avoid cut-off timing misses.  

Types of mutual funds — matched to goals and time horizons

The right fund is never ‘the best fund in India right now’. It is the fund whose risk profile matches your goal’s time horizon. Here is how to think about it:

Fund typeWhat it holdsTime horizonWho it suits
Large-Cap EquityTop 100 companies by market cap — SEBI mandates minimum 80% allocation here5+ yearsFirst-time equity investors who want growth with relatively lower intra-category volatility
Mid-Cap EquityCompanies ranked 101-250 by market cap7+ yearsInvestors comfortable with 30-40% short-term swings in exchange for higher long-term growth potential
Small-Cap EquityCompanies ranked 251+ by market cap10+ yearsSatellite allocation only — high potential, but drawdowns can be severe and recovery can take years
Flexi-Cap / Multi-CapFund manager moves freely across all market cap sizes5-7+ yearsInvestors who want a skilled manager to navigate market cycles without category restrictions
Index Funds (Passive)Mirrors an index — Nifty 50, Nifty Next 50, S&P 500 — mechanically, at very low costAny long-term goalBeginners, cost-conscious investors, anyone who wants set-and-forget market exposure
ELSSEquity fund + Section 80C tax deduction — 3-year mandatory lock-in3+ years minimumTax-saving under old regime AND long-term equity exposure in one instrument
Hybrid / Balanced AdvantageAuto-rebalances between equity and debt based on market valuation signals3-5+ yearsModerate-risk investors who want market participation but with a built-in dampening mechanism
Short-Duration DebtCorporate bonds and government securities under 3-year maturity1-3 yearsGoals too near for equity to recover from a potential drawdown in time
Liquid / OvernightUltra-short money market instruments — near-zero risk0-6 monthsEmergency fund parking — not for growth, but for instant availability at a better yield than savings accounts
Gold / InternationalGold ETFs or overseas indices — satellite diversifiers5+ years5-15% of a portfolio for diversification across asset classes or geographies, not as a standalone strategy

The Goal Ladder — a Finquesta framework for matching funds to your life

Original framework. ‘Match funds to your goals’ is advice given everywhere. This framework shows exactly how — with a rule that most guides miss entirely.

The Finquesta Goal Ladder — five rungs, one rule
Picture your financial life as a ladder. Each rung represents a category of goal, ordered by time horizon.
The governing rule: a lower rung MUST NEVER reach up for a higher return. The emergency fund does not get invested in small-cap equity because ‘returns are better’. Safety is the point of the lower rungs. Return is the point of the upper rungs. Never mix them up.  

RUNG 1 — Emergency floor (0-6 months of expenses, accessible in 24-48 hours):    Vehicle: Liquid fund or overnight fund    The goal here is not to grow — it is to be there.

RUNG 2 — Near-term goals (1-3 years: holiday, appliance, vehicle down payment):    Vehicle: Short-duration debt fund or conservative hybrid    A 30% equity market drop takes 2-3 years to recover. Your 2-year goal cannot wait.  

RUNG 3 — Medium-term goals (3-7 years: property down payment, further education abroad):    Vehicle: Balanced advantage fund, or large-cap equity + short-duration debt in a ratio    Some equity is appropriate — but not 100%, because the recovery window may not be long enough.  

RUNG 4 — Long-term wealth goals (7+ years: retirement, children’s college fund):    Vehicle: Diversified equity — flexi-cap, large-cap, or Nifty 50 index fund in Direct plan    This is where equity works properly, across full market cycles.  

RUNG 5 — Tax efficiency layer (parallel to Rungs 2-4, India old tax regime only):    Vehicle: ELSS for the Section 80C portion of long-term equity allocation    Same equity exposure, with a tax deduction attached. The 3-year lock-in forces patience.   Build the Goal Ladder bottom-up. Fill Rung 1 before touching Rung 4. This order matters more than which specific fund you pick at each rung.

Active funds vs index funds — what the evidence says, and where it’s uncertain

This is the most-studied question in professional investing. Here is what the data shows, where the debate is genuinely unresolved, and what beginners should take from it.

 Active fundsIndex funds (passive)
ManagerHuman fund manager + research teamIndex rules — no human judgment, no manager risk
GoalOutperform the benchmarkMatch the benchmark
Typical Direct plan TER (India)0.5%–1.5% for large-cap active0.05%–0.20% for Nifty 50 trackers
What data showsSPIVA India: over 80% of active large-cap funds underperformed Nifty 100 TRI across 10-year periods. By structural design, matches the index minus the fee. Cannot underperform its own mandate.
Where active may genuinely winMid and small-cap India — less efficiently priced, giving skilled managers real scope to add valueLarge-cap India and most developed markets — too efficiently priced for most managers to consistently add value after costs
The critical benchmark issueMany active funds appear to ‘beat the Nifty 50’ — but the correct benchmark is the Nifty 50 Total Return Index (TRI), which includes dividends reinvested. Measured against TRI, the bar is meaningfully higher and fewer funds clear it.Tracking difference is the honest cost measure for passive funds — it’s the actual annual gap between the fund’s return and the index return, not just the expense ratio
Our viewNeither wins universally. Cost is the only variable you can guarantee before investing. Everything else — manager skill, market efficiency, macro timing — is uncertain.For most beginners, a low-cost Nifty 50 index fund in Direct plan is a well-evidenced starting point.

Costs — the invisible drag that compounds against you

Mutual fund fees are deducted from NAV before it is published. There is no bill. No notification. Over two decades, even a 1% annual fee gap produces a difference of lakhs on the same underlying investment.

Fee impact — what 1.4% per year actually costs over 20 years
Same market, same Rs 1,00,000 invested, two different cost structures:     
Fund A — Direct plan index fund, 0.10% expense ratio → net return ≈ 9.90% p.a.  
Fund B — Regular plan active fund, 1.50% expense ratio → net return ≈ 8.50% p.a.  

   Fund A ending value after 20 years: approximately Rs 6,49,000   
Fund B ending value after 20 years: approximately Rs 4,92,000     

Gap: approximately Rs 1,57,000 — paid entirely in fees to Fund B   
for exposure to the same underlying market.     

What this means: Fund B’s manager needs to outperform Fund A’s gross portfolio by 1.4% per year, every year, for 20 consecutive years — just to break even with you net of costs. That is a very high bar to hold, consistently, across bull markets, bear markets, and every cycle in between.  

Four cost items to check before every investment:

  • Expense Ratio (TER): Always look at the Direct plan TER, not the Regular plan. Available on AMFI (amfiindia.com) or the fund factsheet. For equity index funds today: under 0.20% is achievable. For active large-cap: under 1% in Direct plan is reasonable.
  • Tracking Difference (index funds): More honest than TER alone. It is the actual annual gap between fund return and index return. A fund with 0.15% TER but 0.45% tracking difference costs you 0.45% per year, not 0.15%.
  • Exit Load: Usually 1% if redeemed within 12 months. Read the Scheme Information Document (SID). Not all funds charge an exit load, and some use tiered structures.
  • Tax on gains: Not a fund fee, but as real a cost as TER. Covered in the tax section below.

The Behaviour Gap — why your returns will likely be lower than the fund’s returns

This is probably the most important concept in this entire article — and it appears in almost no Indian beginner guide.

The Behaviour Gap — defined with an uncomfortable illustration
A mutual fund delivers 13% per year over 10 years, measured from the first NAV to the last.
The average investor in that same fund earns 8% per year across the same decade.  

How a 5% gap opens between the fund’s number and the investor’s number:  
  — Markets rise 40% across 18 months. Retail money floods in at the top.   
— Markets fall 30% in a correction. Retail money withdraws at the bottom.   
— SIPs stop in March 2020 when NAVs are at their cheapest.   
— They restart in January 2021 when NAVs have already recovered.  

Every one of those decisions was made for understandable reasons.
Every one of them subtracted from the investor’s actual return.

The 5% gap is not caused by the fund. It is caused by the investor’s own response to price signals. This is the Behaviour Gap — the difference between what an investment earns and what you earn from it.

The implication is not comfortable: the most important investing decision is not which fund to pick. It is whether you will leave the SIP running when every headline tells you to stop it.  

Why point-to-point returns deceive you — and what rolling returns reveal

Every ranking site shows ‘5-year returns from today’. That number describes one specific 5-year window in history. It does not tell you what the fund did in other 5-year windows — which is where the useful information lives.

The point-to-point problem: Fund A returned 22% over 5 years from January 2021 to January 2026. But January 2021 happened to be a market low and January 2026 a market high. Any fund would look good from that starting point. The number measures timing luck as much as manager skill.

Rolling returns — how they remove the timing bias
A 3-year rolling return calculated over 7 years slides a 3-year measurement window across every possible start month:     

Window 1:  Jan 2019 – Jan 2022   →  one 3-year return   
Window 2:  Feb 2019 – Feb 2022   →  another 3-year return  
  Window 3:  Mar 2019 – Mar 2022   →  another   
… 48+ windows total  


Now you can ask the right questions:   
Average 3-year return across all windows?   = consistency across market conditions
  Worst 3-year return?  = downside risk — the number that matters for planning    % of windows where it beat its benchmark?  
= skill measured repeatedly, not once.  


A fund with 12% average rolling 3-year return and +2% as its worst case is far more dependable for a real investor than a fund
with 16% average but -9% worst case.
 Where to find rolling return data: PrimeInvestor.in and ValueResearchOnline. Neither is affiliated with Finquesta — they are
genuinely the best tools for this analysis.

The Fund Overlap test — real diversification vs the illusion of it

Investors who have been investing for 3-5 years often carry 8-12 mutual funds. They feel diversified. In most cases, they are not.

What fund overlap is, and what it costs you
Fund overlap is the percentage of your combined portfolio sitting in identical stocks across multiple funds.  

An example that plays out in thousands of Indian portfolios:   
Fund A (large-cap): 30% of portfolio in HDFC Bank, Reliance, Infosys   
Fund B (flexi-cap):  26% of portfolio in the same three stocks   
Apparent holding: two funds   |   Actual exposure: one concentrated portfolio, counted twice  


What you pay for this illusion:   
Two expense ratios for one portfolio’s worth of exposure   
Extra administrative complexity with no diversification benefit   
When the large-cap sector corrects, both funds fall together — as if you had one fund. The 60% rule: if two funds share more
than 60% of their holdings by weight, one of them is almost certainly redundant.  

How to check:
PrimeInvestor.in Fund Overlap Tool (free). Compare by weight, not just by counting common names.
A shared stock at 0.3% weight barely matters. A shared stock at 9% weight matters a great deal.  

The Finquesta guideline:
three non-overlapping funds — one large-cap or index, one mid/small or flexi, one debt or hybrid — provide all the diversification an
individual investor genuinely needs. More funds add complexity, not protection.

How to start investing — practical steps

India

  • Complete KYC first: Mandatory before any mutual fund investment. PAN + Aadhaar. Most platforms offer eKYC completion in under 10 minutes. If you opened a bank account or demat account recently, check whether you are already verified.
  • Choose Direct plan via Direct channel: Go directly to the AMC website (HDFC MF, Mirae Asset, SBI MF, etc.) or use platforms that offer Direct plans — Groww, Zerodha Coin, Kuvera, MF Central (mfcentral.com). Avoid Regular plan unless you genuinely need an adviser’s ongoing service and the cost is worth it to you.
  • Apply the Goal Ladder: Before choosing a fund, identify which rung of your life it belongs to (see framework above). That determines the fund category. Specific fund selection comes after category selection.
  • Set up SIP with auto-debit: Schedule between the 5th and 25th of the month to avoid NAV cut-off timing issues. Let it run automatically. The discipline of automation is worth more than the decision about which date to choose.
  • Review annually, not after every NAV movement: Check whether your allocation still matches your Goal Ladder once per year, or after a major life change. Do not act on quarterly performance data.

United States

  • Open a brokerage account (Vanguard, Fidelity, Schwab). Use tax-advantaged accounts first — 401(k) via employer for pre-tax contributions, Roth IRA for potential tax-free growth, Traditional IRA as an alternative.
  • ETFs vs mutual funds: for the same index exposure, ETFs often win in a taxable US account because they do not distribute capital gains annually — a structural tax drag that mutual funds create even for investors who did not sell. Vanguard’s comparable ETF and mutual fund typically carry identical expense ratios, so the tax difference is the deciding factor.
  • Target-date funds: one-decision option. Buy the fund matching your retirement year (e.g. 2050 fund) and it shifts automatically from equity-heavy toward debt-heavy as you approach the date. Higher expense ratio than a pure index ETF but lower behavioural risk for investors who prefer to set something and never reconsider it.

Global note

UK: OEICs / unit trusts held in ISAs (tax-free) or SIPPs (pension). Europe: UCITS funds inside pension or investment wrappers. Singapore: unit trusts via CPF or standard cash accounts. Australia: superannuation is the primary vehicle — employer contributions invested in pooled structures by default. The underlying mechanics are identical across all these structures; the tax wrapper, regulator, and contribution rules differ. Verify locally before acting.

The ‘100 minus age’ rule — useful as a starting point, dangerous as a final answer

It is in almost every personal finance article. Almost none of them explain the assumptions it was built on — or why those assumptions no longer hold.

What the rule says
Your equity allocation (%) = 100 minus your age. At 30: 70% equity + 30% debt. At 60: 40% equity + 60% debt. Adjust down by reducing equity as you age.

The rule was built for a world with shorter retirement periods and reliably high fixed-income rates. Three specific things have changed:

  • Longer lives mean longer retirement periods: A 60-year-old in urban India today has a reasonable probability of living to 83-87. That is potentially 25+ years of post-retirement expenses. Allocating 60% to debt at age 60 may protect against short-term volatility but risks running out of purchasing power long before running out of life — particularly with India’s historical 6-8% consumer inflation. The 100-minus-age formula does not account for longevity risk at all.
  • The base number is wrong for many people: Many financial advisers now use 110 minus age or 120 minus age for investors with good health, any guaranteed income source (pension, rental income, EPF), or no dependents. The exact number should come from your specific income floor and expected expenses in retirement, not a universal shortcut.
  • Debt is not equivalent to ‘safe’: Interest rate risk in long-duration debt funds, credit risk in corporate bond funds, and the Franklin Templeton India 2020 liquidity event remind investors that ‘debt = safe’ is a simplification. A conservative investor who shifts into long-duration debt because it feels safe can lose 8-10% in a rising rate environment. Safe means matched to your time horizon, not just labelled as non-equity.

How to use the rule: Treat it as a first approximation only. Then adjust based on three factors: how many years you expect to spend in retirement, whether you have guaranteed income sources to cover basic expenses, and your genuine ability — not theoretical — to hold a 30% portfolio drop without selling. Someone with a pension covering basic expenses can afford more equity at 65 than someone relying entirely on their accumulated corpus.

Tax on mutual fund gains — India and US overview

Jurisdiction note Tax rules differ completely between countries and change frequently. The India figures below are sourced from 2026 search research but all items marked must be confirmed on incometax.gov.in or the relevant Finance Act before publishing.

India — equity funds

  • STCG (held under 12 months): Taxed at 20% on gains.
  • LTCG (held over 12 months): Gains above Rs 1.25 lakh per year taxed at 12.5%, without indexation.
  • ELSS: Qualifies for Section 80C deduction up to Rs 1.5 lakh per year (old tax regime only). Gains on maturity subject to LTCG rules above.

India — debt funds (significant recent change)

  • From April 2023: Gains from debt mutual funds are taxed at the investor’s income tax slab rate, for all holding periods. The long-term indexation benefit that previously made debt funds attractive for higher-income investors was removed. This changes the post-tax return calculation significantly for debt fund investors relative to bank FDs.

United States

  • Taxable account: Short-term gains (under 1 year) = ordinary income tax rates. Long-term gains (over 1 year) = preferential rates.
  • Tax-advantaged accounts: Traditional 401(k)/IRA: tax-deferred growth. Roth IRA: potentially tax-free qualified withdrawals.
  • Capital gain distributions: US mutual funds are required to distribute realised capital gains annually, creating a taxable event even if you did not sell any units. ETFs structurally avoid this through in-kind creation/redemption. For US investors with taxable accounts, this is a concrete advantage of ETFs over equivalent mutual funds.

The Inertia Trap — why understanding a mutual fund is not the same as investing in one

Original Finquesta concept. This is the explanation for the most puzzling pattern in personal finance: people who know what mutual funds are, know SIPs exist, know Direct plans are better — and still have not invested.

The Inertia Trap — three self-reinforcing causes
The Inertia Trap is the gap between comprehending a financial product and actually using it. It has three causes that feed each other:  

1. Choice paralysis:   
India has over 2,500 mutual fund schemes across 44 AMCs. Which one is best for me?’ is a question with no clean answer — and when there is no clean answer, the human brain defaults to doing nothing.  
The rational response to uncertainty becomes the enemy of starting. …

2. Perfectionism delay:   
‘I will start investing once I have properly understood everything.’Properly understanding everything takes six months minimum.    By which point markets have moved, your research feels outdated, and you restart. This loop runs indefinitely for some people.  

3. Market-timing fear:   
‘I will wait until the market corrects before starting my SIP.’ This is the most ironic cause. Waiting for a correction to start a SIP    defeats the purpose of a SIP — which was specifically designed to make the question of market timing irrelevant.
The cure is a deliberately undersized first step: one fund, one SIP, Rs 500 per month, today. You can adjust, add, or change everything later. The decision that matters is starting.
A Rs 500 SIP that starts today compounds forward. A Rs 10,000 SIP that starts three years from now does not — because those three years are gone.  
The Inertia Trap is most severe among intelligent, well-informed people, because they have the highest threshold for certainty before acting. Investing offers certainty about costs. It offers nothing else in advance.

Common myths — what is actually true

MythWhat is actually true
A fund with NAV Rs 10 is cheaper / better value than one at Rs 500NAV is a historical price, not a valuation. Buying 1 unit of a Rs 500 NAV fund vs 50 units of a Rs 10 NAV fund gives you identical purchasing power if both funds hold equivalent portfolios. What matters is how NAV grows — not its absolute level today.
A SIP removes market riskA SIP does not remove market risk — it restructures your exposure to timing risk. Instead of one large bet on one market day, you spread smaller bets across months. Your average entry cost typically improves during market falls. But if the market falls and stays down across your entire investment horizon, a SIP will not protect you from loss.
Owning 10 funds is better diversification than 3 fundsNot if those 10 funds hold 70% of the same stocks. Fund overlap is the relevant test, not fund count. Three funds with genuinely distinct mandates and low portfolio overlap serve most investors better than ten funds that are effectively the same portfolio filed under different names.
The fund that topped last year’s chart is a good choice for this yearSelecting funds by recent rank is pattern-matching on noise. A fund leading for 12 months is almost always benefiting from a sector tailwind that will eventually reverse. Historical equity fund returns reflect the specific economic conditions of those years, not a promise about the years ahead.
Stopping your SIP during a market crash is the prudent responseFrom a wealth-building perspective, it is the opposite. A market drop means the same Rs 5,000 SIP buys more units at lower prices — the mechanism that makes SIP cost-effective. Stopping during a crash converts a temporary paper loss into a permanent decision to buy high only. Investors who paused SIPs in March 2020 and restarted later missed the accumulation window that benefited those who continued.
Direct plan and Regular plan give similar results over timeThey do not. The same fund in Direct plan has a lower expense ratio than its Regular plan counterpart — the difference equals the distributor commission. Compounded over 15-20 years, this gap accumulates into a material difference in corpus, for the same underlying portfolio and the same underlying market performance.
Mutual funds are only for long-term stock investingThe risk spectrum in mutual funds runs from near-zero (overnight funds) to very high (small-cap equity). Debt funds, liquid funds, and conservative hybrids serve investors who need capital stability over short or medium horizons.
Mutual fund vs FD: one is always betterDifferent instruments for different purposes. An FD provides a guaranteed, pre-agreed return with DICGC insurance up to Rs 5 lakh per bank per depositor. A mutual fund provides market-linked returns with no guarantee. For a 12-month goal: FD or liquid fund. For a 20-year retirement goal: equity mutual funds have historically delivered superior real returns — but historical returns describe the past, not the future.

Frequently asked questions

What is a mutual fund in simple terms?

A mutual fund is a regulated, pooled investment account. Thousands of investors each contribute money. A professional manager invests the combined amount across a diversified set of assets. You own units — a proportional share of the pool. Returns and losses flow through to all unit holders in proportion to what they hold.

Is investing in a mutual fund safe?

Two different questions are often asked as one. Structurally safe: yes — mutual funds in India are constituted as trusts, regulated by SEBI, and require mandatory daily disclosure. Your money is legally separated from the AMC. Market safe: no — equity mutual funds can and do lose value in the short term. A liquid fund carries near-zero risk; a small-cap equity fund can fall 40% in a market downturn. ‘Safe’ always means safe relative to your time horizon.

Can I lose money in a mutual fund?

Yes, particularly in the short term in equity funds. An investor who bought an equity fund in February 2020 and sold in April 2020 would have lost approximately 25-30% of their capital in that window. Historical data shows Indian equity markets have recovered and grown over sufficiently long periods — but the word ‘sufficiently’ matters. For a 3-year goal, an equity fund is not appropriate. For a 15-year goal, the historical evidence of recovery is strong.

What is SIP and why is it different from just investing monthly?

SIP is not just a payment schedule — it is a structural approach to eliminating timing decisions. By investing a fixed amount regardless of whether NAV is rising or falling, you automatically buy more units when prices are low and fewer when prices are high. This is called rupee cost averaging. The result over time is an average cost per unit that is typically lower than the simple average of all the NAVs across that period. SIP does not guarantee a profit, but it removes the need to predict market direction before investing.

What is the difference between a mutual fund and an FD?

A fixed deposit gives you a contractually guaranteed return. The bank specifies the rate before you invest, and it does not change. An FD is insured by DICGC up to Rs 5 lakh per bank per depositor. A mutual fund gives you market-linked returns. There is no pre-agreed number. For money you need within 1-2 years or cannot afford to see fall in value, an FD or liquid fund is the appropriate choice. For money you can commit for 7+ years and want to grow meaningfully above inflation, an equity mutual fund has historically served investors better — without guaranteeing it will continue to do so.

What is XIRR and why should I know about it?

XIRR is the accurate measure of your SIP’s annualised return. Because each monthly SIP was invested at a different NAV and has been held for a different length of time, a simple percentage return figure does not account for this complexity. XIRR does — it calculates the internal rate of return across all your dated cash flows. If your investment app shows ‘absolute return’ (e.g. ‘87% total gain’) for a SIP, that number cannot be compared to a fund’s published CAGR, to an FD rate, or to any benchmark. Always ask for XIRR when evaluating SIP performance.

How many mutual funds should I own?

Fewer than most people think. Three to five funds with genuinely different mandates and low portfolio overlap cover all the diversification an individual investor needs. One for large-cap or index exposure, one for mid/small-cap if your time horizon allows, one for short-term or defensive allocation. Adding more funds without running a portfolio overlap check typically increases complexity without increasing diversification — and sometimes reduces it.

SIP vs lump sum — which is better?

For a salaried investor with monthly income: SIP, almost always. It removes timing decisions and builds disciplined investing into a routine. For a windfall (bonus, inheritance, asset sale): you can invest it all at once if you have a long horizon and the market is not at an obvious extreme valuation. Alternatively, park the amount in a liquid fund and transfer a fixed amount monthly into your equity fund over 6-12 months — this is called a Systematic Transfer Plan (STP) and is the most structured way to deploy a lump sum without large single-day timing risk.

Disclaimer This article is for informational and educational purposes only and does not constitute financial, investment, tax, or legal advice. Figures, rates, and regulations mentioned are subject to change; please verify current details with official sources (RBI, SEBI, the Income Tax Department, IRS, or a licensed financial advisor) before making financial decisions. Finquesta may earn a commission from affiliate links in this article at no extra cost to you.